Learning how to unfreeze your credit is important when you’re ready to apply for a mortgage, auto loan, credit card, or other financing. A credit freeze helps restrict access to your credit reports, but legitimate lenders may need that access before approving a new application.
The good news is that you don’t have to permanently remove your protection. In this guide, you’ll learn how to temporarily lift or remove a credit freeze with Equifax, Experian, and TransUnion, how long the process takes, and how to protect your identity while your credit is unfrozen.
Table of Contents
🔥 Quick Answer: How to Unfreeze Your Credit
If you’re applying for a credit card, auto loan, mortgage, apartment, or another service that needs to check your credit, you may need to temporarily lift your credit freeze first. Knowing how to unfreeze your credit lets you give a lender access when necessary without permanently giving up the protection your credit freeze provides.
You manage your credit freeze separately with Equifax, Experian, and TransUnion. If you know which credit bureau the lender plans to check, you may only need to lift the freeze with that bureau. If you don’t know which bureau will be used, you may need to unfreeze your credit with all three. The Federal Trade Commission (FTC) confirms that placing, lifting, and removing a credit freeze is free.
The basic process is straightforward:
- Find out which credit bureau the lender or company plans to check, if possible.
- Sign in to your account with the appropriate credit bureau.
- Choose whether you want to temporarily lift your freeze or permanently remove it.
- If you’re temporarily lifting it, select how long you want your credit report to remain accessible.
- Complete the bureau’s identity-verification process.
- Confirm the freeze has been lifted before submitting your credit application.
- Once the credit check is complete, make sure your credit is protected again.x
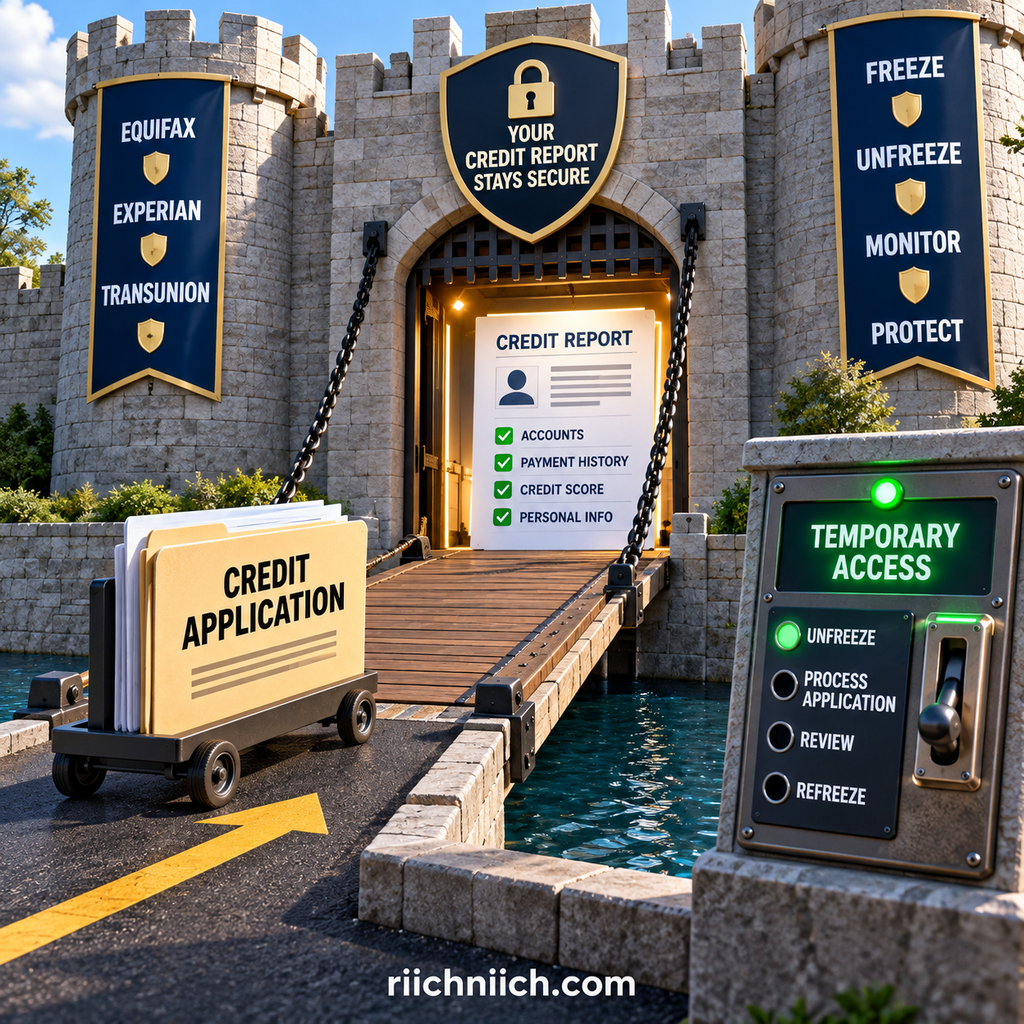
For most people who only need their credit available for an upcoming application, a temporary credit freeze lift can be more practical than permanently removing the freeze. You can open access when it’s needed and then have the protection restored rather than leaving your credit report continuously available.
Knowing how to unfreeze your credit also doesn’t mean you should leave your credit unfrozen longer than necessary. Once the lender has successfully completed the credit check, keeping your reports frozen can continue making it more difficult for an identity thief to open certain new accounts using your information.
However, a credit freeze is only one layer of identity protection. It doesn’t monitor every use of your personal information, prevent fraud on existing accounts, or alert you to every sign of identity theft.
That becomes especially important if your Social Security number, driver’s license information, email address, or other personal data has already been exposed. In that situation, credit monitoring or a more comprehensive identity theft protection service may provide additional monitoring and alerts, depending on the service and plan you choose.
The goal isn’t to keep your credit accessible indefinitely. It’s to open access only when you need it, complete the legitimate credit check, and then restore the protection around your credit reports. That approach gives you more control while still allowing you to apply for new credit when necessary.
What Does It Mean to Unfreeze Your Credit?
Unfreezing your credit means allowing a credit bureau to make your credit file accessible again so a prospective lender or creditor can review it. A credit freeze normally restricts new creditors from accessing your credit file, which can make it harder for an identity thief to open a new credit account in your name.
If you haven’t protected your reports yet, follow our step-by-step guide on how to freeze your credit at all three credit bureaus before deciding when to lift that protection.
When you learn how to unfreeze your credit, you generally have two choices: temporarily lift the freeze or remove it altogether. A temporary lift gives you more control because you can specify a period when your credit file will be available and then have the freeze restored afterward. Permanently removing the freeze leaves your credit file unfrozen until you decide to place another freeze.
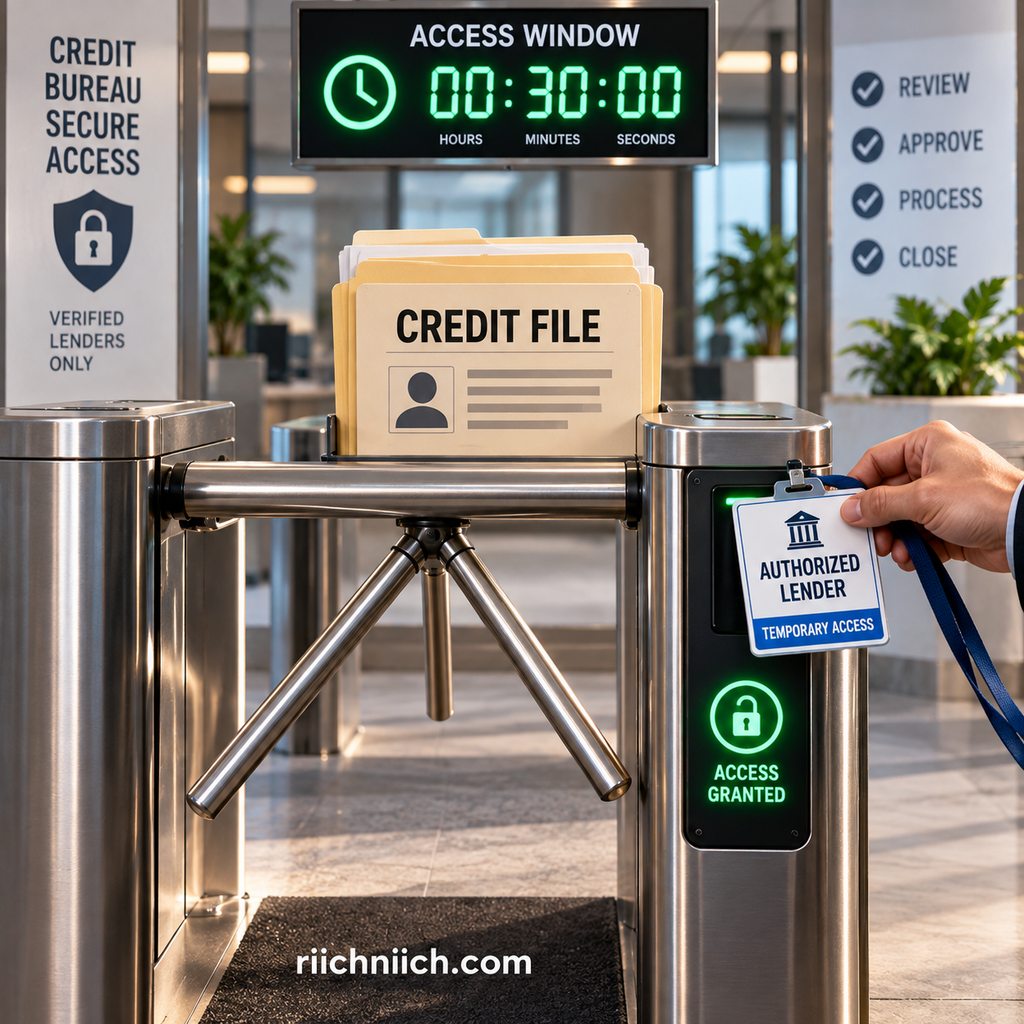
Think of your credit freeze like an access badge protecting a restricted area. The freeze doesn’t erase your credit report or close your existing accounts. Instead, it limits access by prospective creditors. Unfreezing it temporarily is like activating a visitor badge for an authorized lender—you allow access when you need it without permanently removing the security around your credit file.
Temporary Lift vs Removing the Freeze
The difference is important.
A temporary credit freeze lift is designed for situations where you know you’ll need your credit checked, such as applying for a new credit card, financing a vehicle, or getting a mortgage. You choose a period for the lift, and the freeze can return after that period ends.
Removing the freeze completely means the credit report remains unfrozen until you place a new security freeze yourself.
If you can find out which credit bureau a lender intends to use, the FTC says you can lift the freeze only at that particular bureau instead of automatically lifting all three.
Unfreezing Your Credit Doesn’t Cancel Your Existing Accounts
Another important part of understanding how to unfreeze your credit is knowing what the process does not do.
Lifting a credit freeze doesn’t close or reopen your credit cards, change your balances, or erase information from your credit report. A freeze is primarily about restricting prospective creditors’ access to your credit file. You can still review your own credit reports while a freeze is active, and a security freeze doesn’t affect your credit score.
It also shouldn’t be confused with a fraud alert or credit lock. These are different tools with different purposes.
Why Protection Still Matters After You Unfreeze Your Credit
Unfreezing your credit removes an important barrier to certain types of new-account fraud while the freeze is lifted. That doesn’t mean you should avoid applying for legitimate credit—it means you should be deliberate about when and for how long your credit is accessible.
A credit freeze also isn’t complete identity theft protection. Even while your credit is frozen, criminals may still attempt fraud involving existing accounts, which is why the FTC recommends continuing to monitor bank, credit card, and other financial statements for activity you don’t recognize.
If your personal information has already appeared in a data breach or you have reason to believe it has been stolen, this is where additional monitoring can become useful. A credit or identity monitoring service may provide alerts about certain changes or suspicious activity, depending on the service and plan. However, the CFPB cautions that monitoring services don’t prevent every form of identity theft, so they should be viewed as another layer rather than a replacement for a credit freeze.
Ultimately, how to unfreeze your credit is about controlling access—not abandoning protection. Open your credit file when a legitimate lender needs it, limit that access when possible, and continue monitoring your identity and financial accounts so one necessary credit check doesn’t mean leaving the rest of your personal information unprotected.
When Should You Unfreeze Your Credit?
You should generally unfreeze your credit when a legitimate lender or creditor needs access to your credit report to process a new credit application. If you’re learning how to unfreeze your credit, the key is to lift the freeze when access is actually needed rather than leaving your credit reports open indefinitely.
A credit freeze restricts prospective creditors from accessing your credit file. Because lenders typically need to review your credit before approving new credit, an active freeze can prevent an application from moving forward until the appropriate credit report is available.
Common situations where you may need to temporarily lift your credit freeze include:
- Applying for a new credit card
- Financing or leasing a vehicle
- Applying for a mortgage or refinancing
- Applying for a personal loan
- Opening certain new financial accounts
- Requesting financing for a major purchase
- Applying for another type of credit that requires a hard credit inquiry
The FTC recommends finding out which credit bureau the lender intends to use when possible. If the lender only needs one bureau, you can lift the freeze at that bureau instead of automatically unfreezing all three.
Unfreeze Your Credit Before the Lender Checks It
Don’t wait until you’re standing at a dealership or halfway through an online loan application to think about your freeze.
If you know a lender will need your credit report, determine which bureau it plans to check and arrange the temporary lift beforehand. Under federal requirements, a nationwide credit reporting company must lift a security freeze within one hour after receiving an eligible request by telephone or secure electronic means. Requests made by mail can take up to three business days after receipt.
That doesn’t necessarily mean you should unfreeze your credit days or weeks in advance. A temporary lift lets you choose a period when the freeze is removed and then have the protection restored.
For someone researching how to unfreeze your credit, this can provide a useful balance: give the legitimate lender enough time to complete the credit check while minimizing how long your report remains available to prospective creditors.
You Don’t Need to Unfreeze Your Credit for Everything
Having a credit freeze doesn’t mean you need to lift it every time you use your credit.
You generally don’t need to unfreeze your credit simply to continue using an existing credit card, check your own credit report, or manage accounts you already have. The CFPB notes that existing creditors and certain other entities can still have access while a freeze is active.
There are also situations where federal credit-freeze protections don’t apply in the same way. For example, the CFPB notes that the federal security-freeze law does not apply to credit reports requested for employment, tenant-screening, or insurance purposes.
This is why it’s useful to ask the company whether it needs your credit report and which bureau it will use before lifting anything.
Be More Cautious If Your Personal Information Has Been Exposed
If you’ve experienced identity theft or had sensitive information exposed in a data breach, keeping your credit frozen when you aren’t actively applying for credit can provide an important layer of protection against fraudulent new accounts. The FTC specifically identifies identity theft, lost wallets, and data breaches as situations where a freeze can be particularly useful.
In that situation, learning how to unfreeze your credit should also include deciding how you’ll monitor your identity while the freeze is temporarily lifted.
Credit and identity theft monitoring services can provide additional alerts and monitoring, depending on the provider and plan. They don’t replace a credit freeze, but they can complement it by helping you watch for certain suspicious changes involving your credit or personal information.
The safest approach is usually about controlled access. Temporarily lift your freeze when a legitimate credit check requires it, keep the access window as limited as practical, and restore the freeze when the need for the credit check has passed. That way, you can continue applying for the financial products you need without unnecessarily leaving your credit file accessible.
What Information Do You Need to Unfreeze Your Credit?
Before you learn how to unfreeze your credit, it helps to have your personal information ready. Each credit bureau must verify that you’re actually the person requesting access to the credit file before it processes the request.
The exact verification process can vary depending on the credit bureau and whether you make the request online, by phone, or by mail. In general, you should be prepared to provide identifying information such as:
- Your full legal name
- Your Social Security number
- Your date of birth
- Your current address
- Previous addresses, if requested
- Contact information, such as your phone number or email address
- Login credentials if you already have an online account with the credit bureau
- Additional information or documents if the bureau needs to verify your identity
The Consumer Financial Protection Bureau (CFPB) confirms that you must contact Equifax, Experian, and TransUnion separately to manage freezes on each credit file. Freezing and unfreezing your credit is free under federal law.
Do You Need Your Credit Freeze PIN?
You may remember being told to save a PIN when placing a credit freeze, particularly if you froze your credit years ago. However, you shouldn’t assume that every bureau’s current online process will require the same type of PIN.
The important thing is being able to verify your identity and access the bureau’s freeze-management system. Depending on the bureau and method you use, this may involve signing into an account, providing identifying information, or completing additional verification steps.
If you have an old freeze PIN, keep it available just in case it is relevant to your particular freeze or method of requesting the lift. But don’t panic if you can’t immediately find it—the bureau may provide another identity-verification or account-recovery process.
For broader information about your rights when managing a security freeze, the
Have Your Credit Bureau Accounts Ready
One of the easiest ways to prepare for how to unfreeze your credit is to make sure you can access your accounts with the credit bureaus before you’re sitting in front of a lender waiting for approval.
If you’ve forgotten your username or password, recover your account access ahead of time. This can save frustration when you’re trying to temporarily unfreeze credit for an important application.
It is also a good idea to use a strong, unique password for each account and enable additional account-security features when available. Your credit bureau accounts control access to highly sensitive credit information, so they deserve the same level of protection as your banking accounts.
Know Which Credit Bureau the Lender Will Check
Before lifting anything, ask the lender which credit bureau it plans to use.
This can save you from unnecessarily lifting freezes at all three bureaus. The FTC specifically recommends identifying which bureau a lender will use when possible and lifting the freeze only at that bureau. Once the credit check is finished, you can put the freeze back in place.
For example, if a lender tells you it only needs access to one credit bureau, you may be able to temporarily lift that particular freeze while leaving your other credit files protected.
This is especially useful if your personal information has previously been exposed in a data breach or identity theft incident.
Decide How Long You Need the Freeze Lifted
You should also know whether you want to temporarily lift your credit freeze or permanently remove it.
Federal law allows you to request a temporary lift for a period you specify. When requested by telephone or secure electronic means, a nationwide credit reporting company generally must lift the freeze within one hour. A mailed request can take up to three business days after it is received.
If you’re simply applying for a loan or credit card, temporarily lifting the freeze may give you the access you need without leaving your credit file unfrozen indefinitely.
Protect the Information You Use to Unfreeze Your Credit
The information used to verify your identity—especially your Social Security number, date of birth, addresses, passwords, and account credentials—is exactly the type of information you don’t want falling into the wrong hands.
Always go directly to the legitimate credit bureau when managing a freeze rather than following an unexpected email or text claiming that your credit needs to be “unlocked.”
And if your personal information has already been compromised, consider whether additional identity or credit monitoring makes sense for your situation. Monitoring services can provide alerts about certain changes or suspicious activity, but the CFPB cautions that these services don’t prevent all identity theft and shouldn’t be treated as a replacement for a security freeze.
Having everything prepared before learning how to unfreeze your credit makes the process much easier. Gather your identification information, make sure you can access your credit bureau accounts, determine which bureau the lender needs, and decide how long access should remain available. Then you can lift the appropriate freeze when necessary while keeping control over your credit security.
How to Unfreeze Your Credit With Equifax
If your Equifax credit report is frozen and a lender needs to access it, you can temporarily lift or permanently remove the security freeze through Equifax. When learning how to unfreeze your credit, remember that changing your Equifax freeze affects only your Equifax credit report—it does not automatically unfreeze Experian or TransUnion.
For most people applying for new credit, a temporary lift is the better place to start because you can allow access when it’s needed without permanently removing the protection.
How to Temporarily Unfreeze Your Equifax Credit Report
Equifax allows consumers to manage an existing security freeze through a myEquifax account. Equifax says you can place, temporarily lift, or permanently remove a security freeze for free.
To temporarily lift your Equifax freeze:
- Go directly to Equifax and sign in to your myEquifax account.
- Locate the section for managing your security freeze.
- Choose the option to temporarily lift the freeze.
- Select the dates you want your Equifax credit report available.
- Review your request carefully.
- Submit the temporary lift.
- Confirm the status of your Equifax freeze before the lender attempts its credit check.
You can start with Equifax’s official website rather than clicking an unexpected credit-freeze link received by email or text.
Temporary Lift or Permanent Removal?
These options shouldn’t be confused.
A temporary lift allows your Equifax credit report to become accessible for a specified period. A permanent removal eliminates the security freeze until you decide to place another one.
If you’re applying for a mortgage, auto loan, credit card, or another financial product, you may only need temporary access. Leaving the freeze permanently removed could keep your Equifax credit file accessible to prospective creditors longer than necessary.
This is an important part of understanding how to unfreeze your credit with buyer intent in mind: if you’re shopping for a financial product, find out when the lender expects to pull your credit so you can choose an appropriate temporary access window.
How Fast Does Equifax Have to Lift the Freeze?
You shouldn’t necessarily need to wait several days when making an electronic request.
Under federal requirements, a nationwide credit reporting company must lift a security freeze within one hour after receiving an eligible request through a toll-free telephone number or secure electronic method. If the request is made by mail, the deadline is generally three business days after the bureau receives it.
Still, it can be smart to verify the status before telling a lender to run your credit. That can help prevent a frozen report from interrupting an application.
What If You Can’t Access Your myEquifax Account?
If you can’t sign in, avoid creating multiple accounts or following unofficial links promising to “unlock” your credit.
Start with Equifax’s official account-recovery and security-freeze options. Equifax also supports freeze requests by mail, although mailed requests require additional identifying documentation and take longer to process. Its mail request form provides options for temporarily lifting or permanently removing an existing freeze.
If you’re about to apply for financing, resolve any account-access problems before submitting the application whenever possible. That reduces the chance of a lender attempting to pull your Equifax report while it’s still unavailable.
Should You Leave Equifax Unfrozen After the Credit Check?
Usually, there is little reason to leave a security freeze removed simply because you’ve completed one legitimate application.
A security freeze helps prevent prospective creditors from accessing your credit file, which can make it more difficult for an identity thief to open certain new accounts in your name. However, a freeze doesn’t prevent every form of identity theft, including potential fraud involving accounts you already have.
That limitation is especially important if your Social Security number or other sensitive information has already been exposed. In addition to keeping your credit frozen when access isn’t needed, you may want to consider credit monitoring or identity theft protection that can alert you to certain suspicious activity, depending on the provider and plan.
The main goal of how to unfreeze your credit with Equifax is not to remove your protection permanently. It’s to give a legitimate lender the access it needs, for as long as necessary, and then keep your credit file protected when that access is no longer required.
How to Unfreeze Your Credit With Experian
If your Experian credit report is frozen and you’re preparing to apply for a credit card, mortgage, auto loan, personal loan, or another financial product, you’ll need to make your Experian credit file available before a lender can access it. As part of learning how to unfreeze your credit, you can either temporarily lift your Experian security freeze or remove it permanently.
Experian currently allows you to manage a security freeze through your Experian account. You can toggle your report between frozen and unfrozen or schedule a temporary thaw for a specific date range. Experian says that when you toggle your report to unfrozen online, it will lift the freeze within one hour, although the change may happen much faster.
How to Temporarily Unfreeze Your Experian Credit Report
If you’re only opening your credit report for an upcoming application, a temporary thaw can be more practical than permanently removing the freeze.
Experian’s current process for scheduling a temporary thaw is:
- Sign in to your Experian account or create an account if necessary.
- Go to your security freeze controls.
- Select “Schedule a thaw.”
- Choose “Add a thaw.”
- Select the start and end dates for the temporary lift.
- Select “Schedule thaw.”
- Confirm that the dates are correct before completing your application.
At the end of the scheduled period, the temporary thaw ends and the freeze is reinstated.
You can access the Experian Security Freeze Center directly when you’re ready to manage your freeze.
Should You Temporarily Thaw or Permanently Unfreeze Experian?
The choice depends on why you’re opening access.
If you’re shopping for a mortgage, vehicle loan, credit card, or another financial product, a temporary thaw lets you specify when your Experian report should be available and then automatically restores the freeze afterward. Experian specifically notes that a temporary lift can be useful when you’re comparing multiple lenders for rates and terms.
A permanent removal is different. Your Experian credit file remains unfrozen until you decide to place another security freeze.
If you simply need a lender to perform a legitimate credit check, permanently removing the freeze may provide more access than necessary.
How Long Does Experian Take to Unfreeze Your Credit?
Federal law requires nationwide credit reporting companies to lift a security freeze within one hour after receiving a qualifying request by toll-free telephone or secure electronic means. A request submitted by mail generally must be completed within three business days after it is received.
Experian says an online change may occur nearly instantly, but it’s still smart to confirm that your report shows as unfrozen before asking a lender to run your credit.
This can be particularly important when you’re rate shopping. You don’t want a frozen credit file unnecessarily delaying an application when you’re comparing financing offers.
What If You Can’t Access Your Experian Account?
If you’ve forgotten your login information or can’t access your Experian account, don’t use an unofficial third-party website offering to unfreeze your credit for you.
Experian also accepts security-freeze requests by phone and mail. Experian currently lists 888-397-3742 for phone requests and provides a mailing option for consumers who need to submit a written request. Written requests can require identifying documentation, including your full name, Social Security number, date of birth, address history, government-issued identification, and proof of your current address.
If you know you’re about to shop for a mortgage, vehicle, or another credit product, checking your Experian account access ahead of time can prevent unnecessary delays when you’re ready to apply.
Remember: Experian Is Only One Credit Bureau
Unfreezing Experian doesn’t automatically unfreeze Equifax or TransUnion.
Security freezes must be managed separately at each of the three nationwide credit bureaus. If a lender needs a different report—or plans to check more than one—you may need to temporarily lift the corresponding freezes as well.
Before unfreezing everything, ask the lender which credit bureau or bureaus it intends to check. That can help you avoid opening access to credit reports the lender doesn’t need.
Keep Watching Your Credit After the Thaw
Understanding how to unfreeze your credit with Experian isn’t only about getting your application through. It’s also about deciding what happens after the lender completes its credit check.
A security freeze can help protect against fraudulent new-credit applications, but it doesn’t stop every type of identity theft. Existing-account fraud and other misuse of stolen personal information can still occur. Experian therefore recommends continuing to monitor your credit even when freezes are in place.
This is where credit monitoring or a more comprehensive identity theft protection service may add another layer of protection. Depending on the service and plan, you may receive alerts about certain changes to your credit or other signs that your personal information is being misused.
For most consumers who only need Experian access for a legitimate credit application, the goal is simple: temporarily open the door, allow the necessary credit check, and then restore the barrier. That gives you access to the financial products you’re shopping for without unnecessarily leaving your Experian credit report open afterward.
How to Unfreeze Your Credit With TransUnion
If your TransUnion credit report is frozen and you’re getting ready to apply for a credit card, mortgage, auto loan, or another financial product, you may need to make the report available before the lender checks it. When learning how to unfreeze your credit, remember that TransUnion gives you two main options: temporarily lift the freeze for a specific period or remove it completely.
TransUnion says adding, temporarily lifting, and removing a credit freeze are all free. You can manage the freeze online through the TransUnion Service Center, and TransUnion also provides phone and mail options.
How to Temporarily Lift Your TransUnion Credit Freeze
If you’re only opening your TransUnion report for an upcoming credit application, a temporary lift can be a convenient option because you can choose when access begins and ends.
To temporarily lift your TransUnion freeze online:
- Sign in to your TransUnion Service Center account.
- Go to your credit freeze controls.
- Select “Temporarily Lift Freeze.”
- Enter the dates you want your TransUnion credit report to be unfrozen.
- Review the dates carefully.
- Submit your request.
- Wait a few minutes and verify your freeze status before asking the lender to pull your credit.
TransUnion says you can schedule a temporary lift up to 15 days in advance. Once the temporary period ends, the freeze is automatically placed back on your TransUnion credit report.
You can manage the freeze directly through the TransUnion Credit Freeze Center.
Temporary Lift vs Removing Your TransUnion Freeze
These options have an important difference.
A temporary lift makes your TransUnion credit report accessible during the period you select. Once that period ends, the freeze returns automatically.
Removing the freeze completely makes your TransUnion credit report available until you decide to freeze it again.
If you’re rate shopping for an auto loan, mortgage, or another financial product, you may prefer a temporary lift that covers the period when lenders are expected to check your credit. This can eliminate the need to remember to manually restore the freeze afterward. TransUnion specifically describes temporary lifts as useful when you know the window in which a lender will pull your credit.
How Fast Does TransUnion Unfreeze Your Credit?
TransUnion says an online or telephone freeze removal typically takes effect almost immediately. A temporary lift can also be immediate, although TransUnion recommends waiting a few minutes before having a lender request your report.
Federal law also establishes maximum processing periods. A nationwide credit reporting company generally must lift a security freeze within one hour after receiving an eligible request through a toll-free telephone number or secure electronic method. For a mailed request, the bureau generally has up to three business days after receiving it.
Even if your request appears to process immediately, check your freeze status before telling a lender to proceed. A few extra minutes of verification could prevent an unnecessary delay in your application.
Can You Unfreeze TransUnion by Phone or Mail?
Yes. You don’t have to manage your TransUnion freeze online.
TransUnion currently provides an automated phone line at 888-909-8872 for adding, removing, or lifting a freeze. Consumers who need assistance can also contact TransUnion Consumer Relations at 800-916-8800.
You can also submit a written request by mail. TransUnion says the request should include your name, address, and Social Security number, and additional documentation may be required for verification.
If you’re about to apply for financing, managing the freeze online or by phone may be more practical than using mail because mailed requests can take longer to process.
Unfreezing TransUnion Does Not Unfreeze the Other Bureaus
This is one of the most important things to understand about how to unfreeze your credit.
Removing or temporarily lifting your TransUnion freeze does not automatically lift your freezes with Equifax and Experian. Credit freezes at the three nationwide credit bureaus are managed separately.
Before opening all three reports, ask the lender which credit bureau it intends to use. If it only needs TransUnion, you may be able to leave your Equifax and Experian reports frozen.
Don’t Confuse a TransUnion Credit Freeze With a Credit Lock
A credit freeze and credit lock aren’t exactly the same thing.
TransUnion describes a credit freeze as a free tool provided by the credit reporting agency, while credit-lock functionality can be offered as part of credit monitoring or identity-protection products. TransUnion has also discontinued its own Credit Lock feature within certain TransUnion products and directs consumers toward its free credit freeze instead.
This distinction matters when you’re trying to determine exactly what needs to be changed before a lender accesses your report.
Consider Monitoring After Your Credit Is Unfrozen
A credit freeze can make it more difficult for an identity thief to open certain new accounts in your name, but it doesn’t alert you every time something suspicious happens. TransUnion specifically notes that a credit freeze itself doesn’t provide status alerts.
If your personal information has already been exposed in a data breach or you have a higher concern about identity theft, credit monitoring or identity theft protection may provide another layer of visibility. Depending on the service and plan, that can include alerts about certain credit changes or suspicious uses of your personal information.
The purpose of how to unfreeze your credit with TransUnion isn’t simply to make your report accessible. It’s to control when that access is available. When you’re shopping for credit, open the report when a legitimate lender needs it, keep the access period appropriate for your application, and allow the freeze to protect your credit again when that access is no longer necessary.
Do You Need to Unfreeze Your Credit With All Three Credit Bureaus?
Not necessarily. Whether you need to unfreeze Equifax, Experian, and TransUnion depends largely on which credit bureau the lender plans to use.
When learning how to unfreeze your credit, one of the most useful steps is asking the lender which credit report it intends to check. The Federal Trade Commission (FTC) specifically recommends identifying the bureau a lender will use and lifting the freeze at just that bureau when possible.
For example, if an auto lender tells you it will only pull your TransUnion credit report, you may only need to temporarily lift your TransUnion freeze. Your Equifax and Experian reports can remain frozen.
When You May Need to Unfreeze All Three Credit Bureaus
There are situations where temporarily lifting all three freezes may make sense.
If the lender won’t tell you which bureau it will use, you may need to make all three credit reports accessible to avoid having the application delayed. The FTC notes that if you can’t determine which bureau a business will contact, you may need to request a lift from all three bureaus.
You might also consider temporarily lifting all three when:
- You’re shopping among several lenders that may use different credit bureaus.
- A lender tells you it needs reports from multiple bureaus.
- You’re applying for a financial product where several credit reports may be reviewed.
- You don’t know which bureau will receive the credit inquiry.
This can be particularly relevant when you’re shopping for a major financial product. Instead of permanently removing your freezes, you can establish a temporary window that gives legitimate lenders time to complete their credit checks.
Ask the Lender Before Unfreezing Everything
Before you unfreeze credit at all three bureaus, ask one simple question:
“Which credit bureau or bureaus will you use to check my credit?”
If the lender gives you a specific answer, you can temporarily lift only the necessary freeze.
The FTC’s official credit freeze guidance specifically supports this approach. Credit freezes are free to lift, and a temporary lift can be restored once the need for the credit check has passed.
Each Credit Freeze Is Managed Separately
One important part of understanding how to unfreeze your credit is recognizing that your three credit freezes aren’t connected.
If you temporarily lift your Equifax freeze, Experian and TransUnion don’t automatically become unfrozen. The CFPB confirms that consumers must manage security freezes separately with each nationwide credit reporting company.
That also means you should keep track of exactly which freezes you lifted and whether you selected a temporary or permanent removal.
A temporary lift can make this easier. Rather than remembering to manually freeze the report again, you can specify a period during which access is allowed.
What If You’re Shopping With Multiple Lenders?
Suppose you’re comparing several auto-loan or mortgage offers. One lender might check one credit bureau while another uses a different one.
In that situation, temporarily lifting all three freezes for an appropriate period may be more convenient than repeatedly changing individual freezes as different lenders attempt to access your reports.
However, don’t automatically assume every application requires all three reports. Ask first.
Should You Keep the Other Credit Reports Frozen?
If a lender only needs one bureau, keeping the other two frozen maintains the access restrictions on those reports.
That’s especially worth considering if your Social Security number or other sensitive personal information has previously been exposed. The FTC recommends credit freezes as a way to make it harder for identity thieves to open new accounts, particularly after identity theft or a data breach.
But a freeze isn’t a complete identity-protection solution. The FTC notes that someone may still commit fraud involving your existing accounts, which is why you should continue reviewing bank and credit card activity even when all three reports are frozen.
For people at greater risk of identity theft, this is also where credit monitoring or a broader identity theft protection service may provide additional value. Depending on the service you choose, monitoring can provide alerts about certain suspicious changes while your credit freezes continue serving as a barrier against new-account fraud.
Understanding how to unfreeze your credit is ultimately about controlling access. If one bureau is all a lender needs, you don’t necessarily have to open all three. If multiple reports are required, temporarily lift the necessary freezes, complete your applications, and keep your credit protected once lenders no longer need access.
Temporary Credit Freeze Lift vs Permanent Removal
When learning how to unfreeze your credit, one of the most important decisions is whether you should temporarily lift your credit freeze or remove it completely. Both options allow prospective creditors to access your credit file again, but they work differently.
A temporary credit freeze lift removes the restriction for a period you choose. Once that period ends, the freeze goes back into effect. A permanent removal ends the freeze and leaves your credit file unfrozen until you actively place another freeze. The CFPB confirms that both temporary and permanent removals are free under federal law.
For many people who are simply applying for a new financial product, a temporary lift provides the access they need without requiring them to remember to place another freeze afterward.
What Is a Temporary Credit Freeze Lift?
A temporary lift—sometimes called a temporary thaw—allows your credit report to become accessible for a specific period.
For example, suppose you’re shopping for an auto loan and expect lenders to check your credit over the next several days. You could temporarily lift the appropriate freeze during that period rather than removing it indefinitely.
The FTC recommends temporarily lifting a freeze when you need to apply for new credit and putting the freeze back in place when lenders no longer need access.
This can be useful when you’re:
- Applying for a credit card
- Shopping for an auto loan
- Applying for a mortgage
- Refinancing an existing loan
- Applying for a personal loan
- Comparing financing offers from several lenders
If you know which credit bureau the lender will use, the FTC recommends lifting the freeze only at that bureau rather than automatically opening access to all three reports.
What Does Permanently Removing a Credit Freeze Mean?
Permanent removal means the security freeze no longer restricts prospective creditors from accessing that credit file.
There is no automatic date when the freeze comes back.
If you later decide you want the protection again, you’ll need to place a new security freeze. The FTC explains that a credit freeze normally stays in effect until you decide to lift it.
Permanently removing a freeze may make sense if you expect frequent legitimate credit checks and don’t want to repeatedly manage temporary lifts. However, convenience comes with a tradeoff: you no longer have that freeze restricting access to your credit file.
Which Option Makes More Sense When Applying for Credit?
If your goal is simply to let a legitimate lender check your credit, consider a temporary lift first.
For example, if you’re buying a vehicle this weekend, you could arrange for the appropriate credit report to be available during the period when you expect dealerships or lenders to perform their credit checks.
Once that period ends, the freeze can return.
That gives you the convenience of shopping for financing without intentionally leaving your credit report unfrozen indefinitely.
The Consumer Financial Protection Bureau’s credit-freeze guidance explains that consumers can specify the period for a temporary lift and that there is no charge for doing so.
How Quickly Can You Temporarily Lift a Freeze?
You don’t necessarily need to permanently remove your freeze because you’re worried that a temporary lift will take too long.
Under federal requirements, a nationwide credit reporting company must remove a freeze within one hour after receiving an eligible request by toll-free telephone or secure electronic means. That same deadline applies to temporary lifts. Requests submitted by mail generally must be processed within three business days after they’re received.
Still, it’s smart to arrange the lift before a lender attempts to pull your report and verify that your freeze status has changed.
Temporary Lift vs Permanent Removal: Which Provides More Control?
A temporary lift generally provides more control when you know your credit only needs to be accessible for a limited period.
You can think of the difference this way:
Temporary lift: “Open access for now, then restore my freeze.”
Permanent removal: “Remove the freeze and leave my credit report unfrozen until I decide otherwise.”
That distinction becomes especially important if your Social Security number or other sensitive information has previously been exposed. A credit freeze can make it harder for an identity thief to open certain new accounts because prospective creditors typically need access to your credit report.
However, neither option protects you from every type of identity theft. A freeze doesn’t prevent a criminal from attempting to misuse existing accounts, so you should continue monitoring your bank accounts, credit cards, and other financial activity.
If your personal information has already been compromised, this is also where a credit monitoring or identity theft protection service may provide additional value. Depending on the provider and plan, monitoring can alert you to certain suspicious changes while your credit freeze serves as a separate barrier against new-account fraud.
The Bottom Line
For most situations where you’re temporarily shopping for new credit, you don’t necessarily need to remove your freeze permanently.
The key to how to unfreeze your credit is giving legitimate lenders access when they need it without leaving that access open longer than necessary. A temporary credit freeze lift can accomplish exactly that: choose an appropriate access period, complete your credit application or rate shopping, and allow the freeze to return afterward.
Permanent removal remains available when you genuinely want the freeze gone. But if your only reason for unfreezing is an upcoming mortgage, auto loan, credit card, or other credit application, a temporary lift gives you a straightforward way to maintain more control over access to your credit file.
How Long Does It Take to Unfreeze Your Credit?
If you request the change online or by phone, unfreezing your credit can be relatively fast. Under federal law, a nationwide credit bureau must lift a security freeze within one hour after receiving a valid request through a toll-free telephone number or secure electronic method. If you submit your request by mail, the bureau generally has up to three business days after receiving it to lift the freeze.
That means learning how to unfreeze your credit doesn’t necessarily require planning days in advance when you’re applying for a credit card, auto loan, mortgage, or another financial product. However, giving yourself some extra time can help prevent a frozen report from delaying your application.
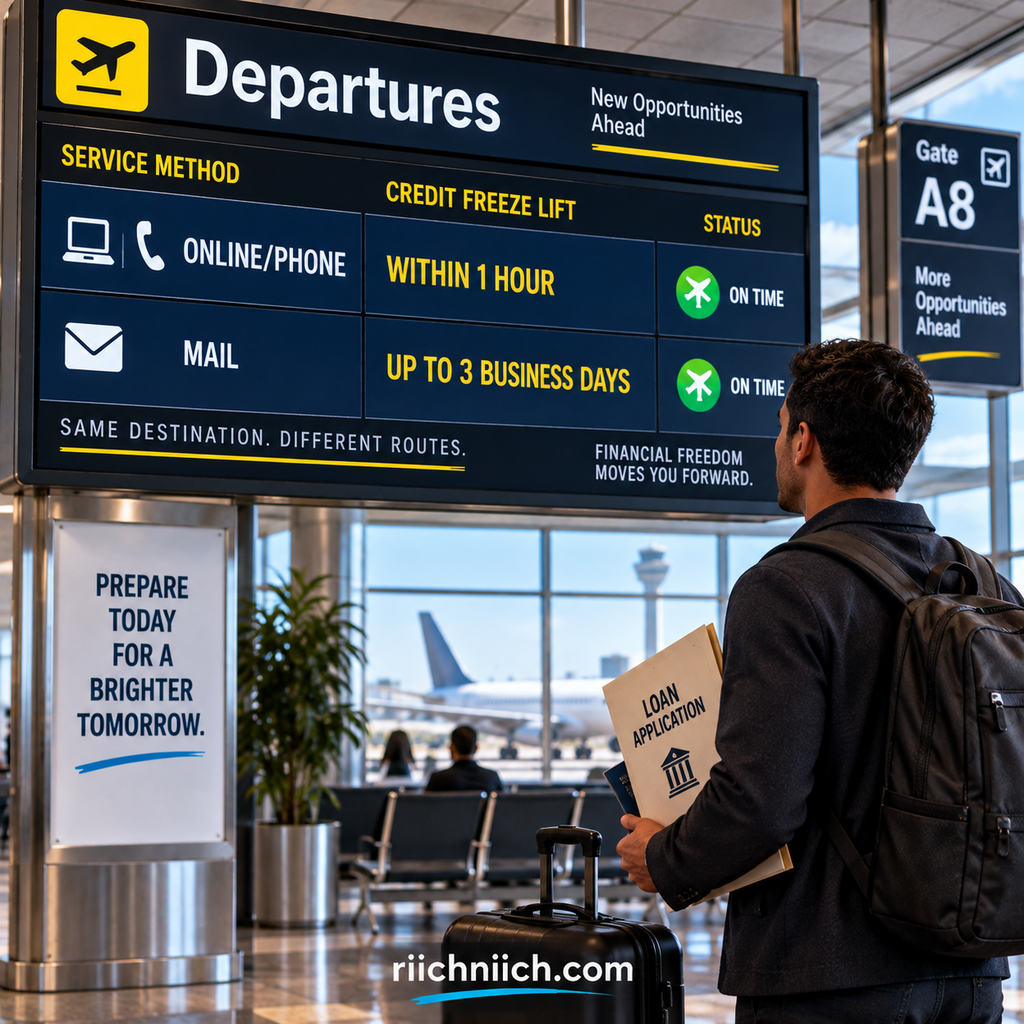
How Fast Is an Online Credit Unfreeze?
Online requests can take effect quickly, although the exact experience can vary by bureau and situation.
For example, TransUnion says adding or removing a freeze online or by phone typically takes effect almost immediately. A temporary lift can also be immediate, though TransUnion recommends waiting a few minutes before having a lender request your report.
Experian states that when you toggle your Experian report from frozen to unfrozen through your account, it will lift the freeze within one hour.
Regardless of how quickly the change appears, don’t assume the lender can immediately access your report. Check your freeze status first, especially if you’re about to submit an important financing application.
Should You Wait Before Applying for Credit?
If possible, yes.
You don’t necessarily need to unfreeze your credit several days ahead of time, but giving yourself a reasonable buffer can prevent unnecessary problems.
Imagine you’re at a dealership negotiating financing and the lender tells you it needs to pull your TransUnion report. You submit the temporary lift while sitting at the finance desk. Even though the request may process quickly, an account-verification issue or forgotten password could slow you down.
A better approach is to ask the lender which credit bureau it plans to use before the credit check. The FTC recommends identifying the bureau the lender will use and lifting the freeze at that bureau when possible.
FTC’s official credit freeze guidance before applying if you want additional information about managing your freeze.
Does It Take Longer to Unfreeze All Three Credit Bureaus?
Equifax, Experian, and TransUnion maintain separate credit files, so you must manage each freeze separately.
If a lender needs access to all three reports, you’ll need to submit the appropriate request to each bureau. The one-hour federal deadline for qualifying online or telephone requests applies to nationwide credit reporting companies individually.
This is another reason to make sure you can access all three accounts before you begin shopping for financing.
If you’ve forgotten a password, can’t complete identity verification, or discover that your contact information is outdated, resolving those problems could take longer than the actual freeze lift.
How Long Does a Mailed Request Take?
Mail is the slowest option.
A nationwide credit bureau generally has up to three business days after receiving your request to lift the freeze. That clock starts when the bureau receives the request—not necessarily when you put the envelope in the mail.
You also have to account for mailing time in both directions and the possibility that additional identity-verification documentation may be required.
If you’re planning to apply for financing soon, an online or telephone request may therefore be more practical when those options are available to you.
What If Your Credit Is Still Frozen After an Hour?
First, verify that your request was successfully submitted.
Sign back into the credit bureau’s account and check the status of your freeze. Also confirm that you changed the correct credit bureau. If a lender is trying to access Equifax but you only lifted TransUnion, the lender may still encounter a frozen report.
You should also confirm that the temporary lift has actually started. If you scheduled the lift for a future date, your credit report may remain frozen until that date arrives.
If the request should already be active but the report remains frozen, contact the credit bureau directly rather than repeatedly submitting new requests.
How Long Should You Keep Your Credit Unfrozen?
Speed isn’t the only consideration when deciding how to unfreeze your credit.
You also need to decide how long the lender needs access.
If you’re applying with one lender, you may only need a short temporary lift. If you’re shopping among several mortgage or auto lenders, you may want an access period that gives the lenders enough time to complete their credit checks.
A temporary lift can be particularly useful because the freeze can automatically return after the period you select. TransUnion, for example, allows consumers to specify the dates for a temporary lift and automatically restores the freeze when the selected period ends.
If you’re shopping for a loan, mortgage, credit card, or other financial product, the practical approach is to prepare before the lender runs your credit. Make sure you can access the appropriate bureau, submit the temporary lift, verify that it took effect, and then proceed with the application.
Once you understand how to unfreeze your credit, the process itself can be fast. The bigger goal is making sure your legitimate credit application gets through without leaving your credit report accessible longer than necessary.
How Long Should You Leave Your Credit Unfrozen?
There is no universal number of days that everyone should leave their credit unfrozen. A better approach is to keep your credit report accessible only for as long as a legitimate lender needs to complete the credit check.
When learning how to unfreeze your credit, think in terms of an access window. If one lender only needs to pull your credit once, that window may be short. If you’re comparing several lenders for a mortgage or auto loan, you may need a longer temporary lift so each lender has enough time to access the appropriate report.
Federal rules allow you to temporarily lift a security freeze for a period you specify, and the freeze can return after that period ends.
Keep the Unfreeze Period as Long as Necessary—But No Longer
Suppose you’re applying for a single credit card and the issuer tells you it plans to check your credit that day. You may not need to leave your report unfrozen for an extended period.
But imagine you’re shopping for a mortgage and several lenders may need to review your credit over multiple days. A longer temporary lift may be more practical because you don’t want your freeze returning before legitimate lenders have completed their checks.
Before choosing your dates, ask the lender:
“When do you expect to pull my credit, and which credit bureau will you use?”
The FTC recommends identifying which bureau the lender plans to check when possible. You can then lift the freeze at that bureau and put the freeze back in place once the need for the credit check has passed.
Should You Leave Your Credit Unfrozen for Several Days?
You can if that’s what your application requires.
For example, a temporary lift lasting several days could make sense if you’re actively comparing financing offers and aren’t certain exactly when the lenders will run their credit checks.
The key isn’t choosing an arbitrary number such as one, three, five, or seven days. It’s choosing a period that realistically covers your application.
The CFPB confirms that consumers can specify the period for a temporary credit freeze lift, and there is no charge for doing so.
For additional details about temporary lifts, the
Consumer Financial Protection Bureau’s credit-freeze guidance explains your rights when managing a security freeze.
What If the Lender Hasn’t Pulled Your Credit Yet?
Don’t rush to restore the freeze if the legitimate lender still needs access.
Instead, contact the lender and confirm whether the credit check has been completed. If it hasn’t, determine when it expects to pull your report and adjust your temporary lift if necessary.
This can be especially important when you’re working with multiple lenders, where credit checks may not all happen at the same time.
At the same time, there’s usually little reason to leave your credit unfrozen indefinitely just because you might apply for something later.
The FTC advises consumers to temporarily lift a freeze when they need to apply for new credit and put the freeze back in place when lenders no longer need access.
What If You’re Shopping for a Mortgage or Auto Loan?
This is where planning your temporary lift becomes especially useful.
If you’re comparing mortgage or auto financing offers, ask the lenders which credit bureaus they use and approximately when they expect to check your reports.
You can then schedule an access period that covers your rate-shopping process instead of permanently removing your freezes.
Don’t Permanently Remove a Freeze Just for Convenience
If your only reason for unfreezing your credit is an upcoming application, consider whether you actually need to remove the freeze permanently.
A temporary lift gives you the ability to choose the period during which your report is accessible. Once that period ends, the restriction can return automatically.
That can be particularly valuable if your Social Security number or other sensitive personal information has previously been exposed. A credit freeze makes it harder for an identity thief to open certain new accounts because prospective creditors generally can’t access the frozen credit file.
However, a freeze doesn’t protect against every form of identity theft. A thief may still attempt fraud involving your existing accounts, so you should continue reviewing your bank and credit card activity even when your reports are frozen.
This is also where identity theft protection or credit monitoring can add another layer of visibility. Depending on the service and plan, monitoring may alert you to certain suspicious credit changes or potential misuse of your personal information while your credit freeze provides a separate barrier against new-account fraud.
The practical rule for how to unfreeze your credit is simple: give legitimate lenders enough time to complete the credit checks you authorized, but don’t leave your reports accessible indefinitely without a reason. Once the necessary credit checks are finished, restoring the freeze keeps that additional barrier in place while you continue monitoring your credit and identity for suspicious activity.
Can You Unfreeze Your Credit for Just One Creditor?
In some situations, you may be able to limit access to a particular creditor rather than broadly opening your credit file. However, the options available can depend on the credit bureau, your state, and the bureau’s current freeze-management process. A more universally available approach is to temporarily lift the freeze at the specific credit bureau the creditor plans to use. The FTC recommends asking which bureau a lender will check and lifting only that bureau’s freeze when possible.
This is an important part of understanding how to unfreeze your credit because you may not need to make all three credit reports accessible just to complete one application.
For example, suppose you’re financing a vehicle and the lender tells you it will check TransUnion. Instead of unfreezing Equifax, Experian, and TransUnion, you could temporarily lift your TransUnion freeze while leaving the other two frozen.
Ask Which Credit Bureau the Creditor Uses First
Before changing any freeze, ask the creditor:
“Which credit bureau will you use to check my credit?”
That one question can save you from unnecessarily lifting all three freezes.
The FTC specifically says that when you need lenders to access your credit, it’s a good idea to identify which bureau the lender will use and lift the freeze at just that bureau. Once the need for the credit check has passed, you can put the freeze back in place.
You can find additional information through the FTC’s official credit freeze guidance.
Can You Authorize Only One Specific Creditor?
This is where the distinction becomes important.
Some security-freeze procedures have supported a temporary release specifically for a named creditor. Experian consumer materials, for example, describe temporary release procedures in which the consumer identifies either the person who should receive the report or the period during which the report should be available.
But you shouldn’t assume that every bureau’s current online freeze dashboard will offer a simple “allow this creditor only” button. Current consumer-facing systems commonly emphasize temporary lifts based on a date range. TransUnion, for example, currently instructs consumers to enter the dates during which they want the freeze temporarily lifted.
So if your goal is access for one creditor, first check the options offered by the bureau that creditor plans to use. If creditor-specific access isn’t available through that process, a short temporary lift at only the required bureau can accomplish a similar practical goal while keeping your other reports frozen.
One Creditor vs One Credit Bureau
These two concepts are easy to confuse.
One creditor means you’re trying to authorize a particular lender or company.
One credit bureau means you’re temporarily making your Equifax, Experian, or TransUnion report accessible.
The second option is straightforward: credit freezes are maintained separately by the three nationwide credit bureaus. The CFPB confirms that you must contact each bureau separately when managing its freeze.
So if your lender says, “We only need Equifax,” you don’t automatically need to unfreeze Experian and TransUnion.
That can be particularly useful when you’re applying for a single financial product rather than shopping among many lenders.
What If You’re Comparing Multiple Creditors?
Your strategy may change if you’re rate shopping.
If you’re comparing several mortgage, auto-loan, or personal-loan offers, different lenders may use different credit bureaus or may attempt their credit checks at different times.
In that situation, repeatedly opening and closing individual freezes could become inconvenient. A temporary lift covering your expected shopping period may be more practical.
TransUnion, for example, allows you to choose start and end dates for a temporary lift and automatically adds the freeze back at the end of that period.
Why Limit Access When You Can?
If only one credit report needs to be accessible, there is usually no need to lift the other freezes simply out of habit.
A credit freeze prevents prospective creditors from accessing your credit file and can make it harder for an identity thief to open certain new accounts in your name.
That protection can be particularly valuable if your Social Security number or other sensitive information has already been exposed.
At the same time, a credit freeze doesn’t stop every form of identity theft. Existing creditors and certain other entities can still access a frozen report in permitted circumstances, and a freeze doesn’t prevent someone from attempting fraud involving an account you already have.
If you’re concerned that your personal information is already circulating, credit monitoring or a broader identity theft protection service can add another layer of visibility. Depending on the provider and plan, these services may monitor for certain suspicious activity and send alerts while your freezes continue serving as a separate barrier against new-account fraud.
The key to how to unfreeze your credit is to avoid opening more access than your legitimate application requires. Ask which bureau the creditor will use, check whether creditor-specific access is available through that bureau’s process, and otherwise consider a short temporary lift of only the necessary credit report. That lets you move forward with the financial product you’re applying for while keeping as much of your existing credit protection in place as practical.
What Happens After You Unfreeze Your Credit?
After you unfreeze your credit, prospective lenders can once again access the credit report you made available. This allows a bank, credit card issuer, auto lender, mortgage lender, or other creditor to review your credit information when deciding whether to approve your application and what terms to offer.
If you discover that someone opened an account in your name, act quickly to report the fraudulent account, protect your credit, and begin the identity-theft recovery process.
Understanding what happens afterward is an important part of how to unfreeze your credit, especially if you’re shopping for a loan or another financial product. Your credit history isn’t erased or reset when you lift the freeze—the restriction on access is simply removed for the bureau and period you selected.
The Lender Can Check Your Credit Report
Once the appropriate freeze has been lifted, the lender can request your credit report as part of its normal application process.
That may happen when you’re:
- Applying for a new credit card
- Financing a vehicle
- Applying for a mortgage
- Refinancing a loan
- Applying for a personal loan
- Opening another account that requires a credit check
This is why you should confirm which credit bureau the lender plans to use before opening access. The FTC recommends lifting the freeze only at the bureau the lender needs when you can identify it.
Your Credit Score Doesn’t Automatically Change Because You Unfroze Your Credit
Unfreezing your credit by itself doesn’t raise or lower your credit score. The CFPB states that security freezes do not affect credit scores.
However, what you do after lifting the freeze can affect your credit over time.
For example, applying for a new credit product may result in a hard inquiry, and opening a new account can change factors used in calculating your credit score. Those potential changes come from the credit activity—not from the act of unfreezing the report itself.
A Temporary Lift Can End Automatically
If you chose a temporary credit freeze lift, you specify the period during which you want the freeze removed. Once that temporary period ends, the freeze restriction returns.
This can be particularly convenient when you’re shopping for financing.
For example, if you know lenders will need access during a specific period, you can schedule the temporary lift around your applications rather than permanently removing the freeze and having to remember to place another one later.
If you permanently removed the freeze instead, it remains removed until you place a new security freeze.
Your Existing Accounts Continue Working Normally
Unfreezing your credit doesn’t activate, close, or modify your existing credit cards, loans, or bank accounts.
A credit freeze is primarily designed to restrict prospective creditors from accessing your credit file. Even while a freeze is active, existing creditors can still have access in permitted circumstances.
That means lifting the freeze shouldn’t be viewed as “turning your credit back on.” You’re changing an access restriction on your credit report.
Your Credit Report Has Less Protection Against New-Account Fraud While the Freeze Is Lifted
This is the security tradeoff to understand.
A credit freeze can make it harder for an identity thief to open certain new accounts because prospective creditors generally can’t access the frozen credit file. When you lift that restriction, the barrier provided by the freeze isn’t operating in the same way for that report during the lift.
That doesn’t mean you should avoid unfreezing your credit when you legitimately need financing. It means you should avoid leaving your report accessible unnecessarily.
If your Social Security number or other personal information has already been compromised, consider keeping the access window reasonably limited.
Check Whether the Lender Successfully Pulled Your Credit
Don’t immediately assume everything is finished simply because you submitted the unfreeze request.
If you’re applying for an important financial product, confirm that the lender successfully accessed the correct credit report. If the lender hasn’t completed the check yet, restoring the freeze too early could interrupt the application.
This is especially important if you’re comparing several lenders over multiple days.
Once the necessary credit checks are complete, the FTC recommends putting the freeze back in place when lenders no longer need access.
Continue Monitoring Your Credit and Existing Accounts
Knowing how to unfreeze your credit doesn’t eliminate the need to watch your financial accounts.
A credit freeze is primarily aimed at new-account fraud. The FTC warns that even with a freeze in place, an identity thief may still make unauthorized charges on existing accounts. Consumers should continue reviewing bank, credit card, and other financial statements for activity they don’t recognize.
If your personal information has already been exposed, this is where credit monitoring or a broader identity theft protection service may provide additional value. Depending on the provider and plan, these services may monitor for certain credit changes or other signs of identity misuse and send alerts when potentially suspicious activity is detected.
After you understand how to unfreeze your credit, the next step is managing what happens afterward. Give legitimate lenders enough time to complete the credit checks you authorized, verify that the application has moved forward, and then restore the freeze when access is no longer needed. If you’re concerned about identity theft, continue monitoring your credit and financial accounts so your protection doesn’t depend on a credit freeze alone.
What Should You Do If You Can’t Unfreeze Your Credit?
If you’re trying to apply for a mortgage, auto loan, credit card, or another financial product and your credit freeze won’t lift, don’t keep submitting the same request over and over. First, determine why the request isn’t going through and whether the problem involves Equifax, Experian, TransUnion, or more than one bureau.
Problems with how to unfreeze your credit can sometimes come down to account access, identity verification, incorrect personal information, or attempting to lift the wrong bureau’s freeze. Because each credit bureau manages its freeze separately, a problem with one doesn’t necessarily mean there’s a problem with the others.
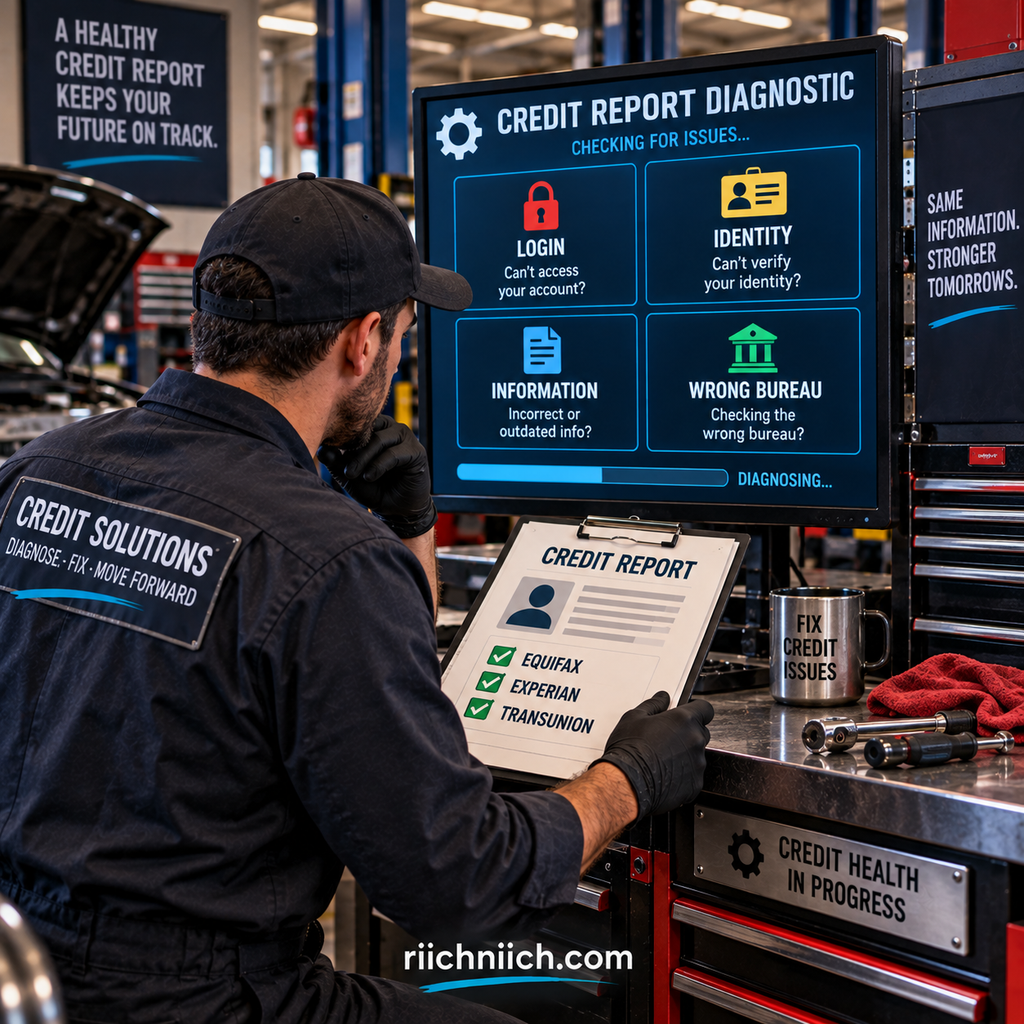
1. Make Sure You’re Unfreezing the Correct Credit Bureau
Start by asking the lender which credit bureau it is trying to access.
For example, you might successfully lift your Experian freeze while the lender is actually attempting to pull your Equifax report. From your perspective, your credit has been “unfrozen,” but the lender still encounters a frozen file.
The FTC recommends finding out which credit bureau the lender plans to use and lifting the freeze at that bureau when possible.
If the lender can’t tell you which bureau it will use, you may need to manage the freezes with all three separately.
2. Check Your Credit Freeze Status
If you submitted a temporary lift online, sign back into the credit bureau’s official website and check its status.
Look for confirmation that:
- The freeze was successfully lifted.
- You selected the correct start date.
- The temporary lift hasn’t already expired.
- You didn’t accidentally schedule the lift for a future date.
- You’re checking the same bureau the lender is attempting to access.
Also save any confirmation number, email, or screenshot showing that your request was submitted. That information may be useful if you need to contact the bureau.
3. Check for an Account or Identity-Verification Problem
If you can’t get into your account, use the credit bureau’s official account-recovery process rather than creating unnecessary new accounts.
You may also encounter additional identity-verification requirements. Be prepared to confirm information such as your name, Social Security number, date of birth, current address, or other identifying information requested by the bureau.
If your information recently changed—for example, you moved or changed your name—the bureau may need additional information before processing your request.
Most importantly, don’t pay an unfamiliar third party to unfreeze your credit for you. Placing and lifting a security freeze is a right provided free of charge under federal law.
4. Try Another Official Method
If the online system isn’t working, you aren’t limited to repeatedly refreshing the website.
The nationwide credit bureaus also provide other methods for managing freezes, including telephone and mail. The FTC maintains official credit-bureau contact information and explains your credit-freeze rights.
Keep timing in mind if you’re applying for financing. A valid freeze-lift request made by toll-free telephone or secure electronic means generally must be completed within one hour. A request made by mail generally must be completed within three business days after the bureau receives it.
5. Tell the Lender There’s a Credit Freeze Issue
If you’re in the middle of an application, communicate with the lender.
Tell them that your credit report is frozen and you’re working with the appropriate bureau to lift it. Ask whether they can wait to run the credit until you confirm that the freeze has been removed.
This is particularly important when you’re shopping for a major financial product. You don’t want repeated confusion between you, the lender, and the credit bureau when the actual problem may simply be that the lender attempted the credit check before the temporary lift became active.
Once you’ve resolved the problem, confirm your freeze status before asking the lender to try again.
6. Contact the Credit Bureau Directly
If you’ve verified that you’re using the correct bureau and the freeze still won’t lift, contact that credit bureau directly.
Explain that you have an existing security freeze and are attempting to temporarily lift or remove it. Have your identification information and any confirmation or reference numbers available.
The FTC advises consumers who are having trouble with a credit freeze to contact the credit bureau first and try to resolve the problem directly.
Keep records of your attempts, including dates, confirmation numbers, correspondence, and what you were told. That documentation can be useful if the problem continues.
7. Escalate the Problem If the Bureau Doesn’t Resolve It
If you’ve contacted the credit bureau and believe it still isn’t properly processing your freeze request, you have another option.
The FTC advises consumers experiencing unresolved problems with credit freezes to submit a complaint to the Consumer Financial Protection Bureau.
The CFPB’s consumer complaint system allows consumers to submit complaints involving credit reporting and other financial products.
This step shouldn’t be necessary for a routine unfreeze, but it’s available if you’ve followed the bureau’s process and the problem remains unresolved.
Be Extra Careful If You Didn’t Place the Freeze
There is one situation that deserves additional attention: you discover a freeze that you don’t remember placing or encounter other unexplained changes involving your credit.
If those warning signs point to actual fraud, follow these steps on what to do immediately if your identity is stolen so you can begin limiting the damage and recovering your identity.
Review your credit reports and financial accounts for activity you don’t recognize. If you discover evidence of identity theft, the federal government’s IdentityTheft.gov service can provide an Identity Theft Report and a personalized recovery plan.
You may also want additional credit or identity monitoring if your personal information has already been compromised. Depending on the provider and plan, an identity theft protection service may monitor certain credit changes and other indicators of identity misuse. However, monitoring doesn’t replace a credit freeze, and the CFPB cautions that identity-monitoring services can’t prevent every form of identity theft.
A problem with how to unfreeze your credit doesn’t necessarily mean you need to abandon the freeze permanently. Verify the correct bureau, check your temporary-lift dates and account information, contact the bureau when necessary, and confirm the freeze has actually been lifted before the lender tries again. Once the legitimate credit check is finished, you can keep using a security freeze as an important layer of protection against fraudulent new accounts.
Should You Freeze Your Credit Again After Applying?
Yes. Once the lender has completed the credit check and no longer needs access to your credit report, putting the freeze back in place can restore an important barrier against fraudulent new accounts. The FTC specifically recommends temporarily lifting a freeze when you need to apply for credit and placing it back when lenders no longer need access.
This is an important final step when learning how to unfreeze your credit. The goal isn’t to leave your credit reports accessible after your application is finished. It’s to give legitimate lenders the access they need and then restore the protection when that access is no longer necessary.
Make Sure the Lender Is Finished First
Don’t restore the freeze immediately after clicking “Submit” on a credit application.
The lender may not have pulled your credit yet. Depending on the application, the credit check could happen later in the process.
Before freezing the report again, ask the lender whether it has successfully completed the credit check. If you’re comparing several financing offers, make sure all authorized lenders that still need your report have finished.
Once they have, you can restore the freeze.
If you’re unsure which bureau was accessed, remember that Equifax, Experian, and TransUnion freezes are managed separately. The CFPB confirms that you must manage the freeze at each nationwide credit reporting company individually.
What If You Used a Temporary Credit Freeze Lift?
If you scheduled a temporary lift for a specific period, you may not need to manually place another freeze.
A temporary lift allows you to specify how long the freeze should remain lifted. When that period ends, the freeze returns. The CFPB confirms that consumers can temporarily lift a security freeze for a period they specify, free of charge.
For example, if you scheduled a temporary lift to cover your loan-shopping period, the freeze can return after that window closes.
This is one advantage of using a temporary lift instead of permanently removing the freeze: you don’t have to rely entirely on remembering to restore the protection yourself.
What If You Permanently Removed the Freeze?
This requires more attention.
If you permanently removed your security freeze rather than temporarily lifting it, the freeze doesn’t automatically return. You’ll need to place another freeze when you want that protection restored. The FTC notes that a freeze remains lifted after permanent removal until you place it again.
Fortunately, placing and lifting security freezes is free.
If you’ve finished applying for credit and don’t anticipate another credit check soon, restoring the freeze can reduce unnecessary access to your credit file.
Do You Need to Freeze All Three Credit Bureaus Again?
If you originally maintained freezes with Equifax, Experian, and TransUnion, check the status of each one after you’re finished applying.
Suppose you temporarily lifted only TransUnion because that’s the bureau your lender used. Your Equifax and Experian freezes should not have been affected because the three freezes are managed separately.
But if you permanently removed freezes from all three, you’ll need to place the freezes individually with all three bureaus if you want to restore that protection across your credit files.
Why Refreezing Your Credit Matters
A security freeze prevents prospective creditors from accessing your credit file. Because lenders generally need that information before opening new credit, the restriction can make it harder for an identity thief to open certain new accounts in your name.
That protection can be particularly valuable if sensitive information such as your Social Security number has already been exposed in a data breach or identity theft incident. The FTC specifically highlights credit freezes as useful in those circumstances.
A Credit Freeze Still Isn’t Complete Identity Theft Protection
Restoring your credit freeze is useful, but it doesn’t mean you can stop watching your accounts.
A security freeze focuses primarily on restricting new creditors’ access to your credit file. It doesn’t prevent an identity thief from attempting to take over or misuse accounts you already have.
That’s why you should continue reviewing your bank accounts, credit cards, credit reports, and other financial activity for transactions or accounts you don’t recognize.
If your personal information has already been compromised—or you simply want more ongoing visibility—you may also consider credit monitoring or a broader identity theft protection service. Depending on the provider and plan, these services can alert you to certain changes or signs of identity misuse. However, the CFPB cautions that monitoring services don’t prevent identity theft, so they should complement rather than replace preventive measures such as a security freeze.
The safest way to approach how to unfreeze your credit is to treat the unfreeze as temporary whenever possible. Give legitimate lenders enough time to complete the credit checks you authorized, confirm they’re finished, and then restore the freeze. That lets you shop for the credit products you need without unnecessarily giving up the protection of a frozen credit file afterward.
Does Unfreezing Your Credit Leave You Vulnerable to Identity Theft?
Unfreezing your credit can temporarily remove an important barrier against new-account identity theft, but it does not mean identity theft will automatically happen. When a security freeze is active, prospective creditors generally cannot access your credit file. Once you lift that freeze, authorized lenders can access the report again—and that means the freeze is no longer providing the same restriction against someone attempting to open new credit in your name.
That’s why understanding how to unfreeze your credit is about more than getting a lender through the door. You also want to control how long that door stays open, especially if your Social Security number or other sensitive personal information has previously been exposed.
A credit freeze is only one layer of security, so learn how to protect yourself from identity theft across your financial accounts, personal information, and online activity.
What Protection Do You Lose When You Unfreeze Your Credit?
A credit freeze is primarily designed to make it harder for identity thieves to open new credit accounts in your name.
Most lenders want to review your credit report before approving a new account. When your report is frozen, that access is restricted, which can prevent a fraudulent credit application from moving forward. The FTC describes a credit freeze as particularly important when your Social Security number or other information has been exposed in a data breach or already misused.
When you temporarily lift your freeze, that restriction is removed from the affected credit file for the period you selected.
That creates an access window for your legitimate application—but it also means the freeze isn’t providing its usual new-account barrier during that period.
Does That Mean Someone Can Immediately Steal Your Identity?
No.
Unfreezing a credit report doesn’t hand your Social Security number, passwords, or financial information to criminals. It simply changes whether prospective creditors can access that particular credit file.
For someone to commit identity theft, they would still need enough of your personal information to impersonate you or otherwise commit fraud.
The risk deserves more attention if your personal information has already been compromised. For example, if your Social Security number, date of birth, or other identifying information was exposed in a data breach, an active credit freeze can be an especially useful safeguard against fraudulent new-credit applications.
Keep the Unfreeze Window as Short as Practical
One way to reduce unnecessary exposure is to temporarily lift your credit freeze instead of permanently removing it when you only need access for an application.
The CFPB confirms that you can request a temporary lift for a period you specify, free of charge.
For example, if you’re applying for an auto loan and the lender expects to pull your credit during the next few days, you could schedule your temporary credit freeze lift around that application rather than leaving your credit report accessible indefinitely.
You can also ask which credit bureau the lender plans to use. The FTC recommends lifting the freeze at only that bureau when possible and putting the freeze back in place once the credit check is no longer needed.
Your Other Credit Reports Can Remain Frozen
Unfreezing one credit bureau doesn’t automatically unfreeze the others.
Equifax, Experian, and TransUnion maintain their security freezes separately. If your lender only needs one report, you may be able to temporarily lift that bureau’s freeze while leaving the other two protected.
This can be useful when you’re applying for a single financial product and know exactly which report the creditor intends to check.
Instead of thinking of how to unfreeze your credit as an all-or-nothing decision, think of it as granting only the access your legitimate application requires.
A Credit Freeze Doesn’t Protect You From Every Type of Identity Theft Anyway
This distinction is important.
Even when all three credit reports are frozen, an identity thief may still attempt to misuse an existing account. The CFPB and FTC both warn that a credit freeze doesn’t prevent someone from taking over or making unauthorized charges on accounts you already have.
A freeze also doesn’t protect every piece of personal information you have.
That’s why identity protection should be layered rather than relying on a credit freeze alone.
You should still:
- Review bank and credit card transactions.
- Check your credit reports for unfamiliar accounts.
- Use strong, unique passwords on important accounts.
- Enable two-factor authentication where available.
- Watch for suspicious account alerts.
- Protect your Social Security number and other sensitive information.
The freeze is one strong layer—particularly against new-credit fraud—but it isn’t an all-purpose identity theft prevention system.
Should You Monitor Your Credit While It’s Unfrozen?
If your personal information has already been exposed or you regularly worry about identity fraud, additional monitoring may be worth considering while your credit is accessible.
You can review your credit reports yourself, and some financial institutions provide certain credit-monitoring features. You may also consider a dedicated identity theft protection service if you want broader monitoring and alerts.
Depending on the provider and plan, these services may monitor certain credit-file changes or other indicators of identity misuse. Some services also include recovery assistance if identity theft occurs.
However, monitoring and a credit freeze serve different purposes. The CFPB notes that identity-monitoring services may alert consumers to certain suspicious activity, while a security freeze can generally prevent new credit from being opened because prospective creditors can’t access the frozen report.
What If Your Information Was Already Exposed in a Data Breach?
This is where you should be particularly careful about leaving your credit unfrozen longer than necessary.
The FTC recommends credit freezes as a protective measure after sensitive information is exposed because they can make it harder for identity thieves to open new accounts.
If you need financing after a breach, you don’t necessarily have to permanently sacrifice that protection.
Temporarily lift the necessary freeze, complete the legitimate credit check, and restore the freeze afterward.
If you believe someone is already using your identity, the CFPB recommends reporting the theft through the federal government’s identity-theft recovery process and taking additional steps such as closing compromised accounts and considering fraud alerts or security freezes.
Knowing how to unfreeze your credit doesn’t mean choosing between accessing credit and protecting your identity. The better approach is controlled access: lift only the freeze a legitimate lender needs, keep the access period as short as practical, restore the freeze when the credit check is finished, and continue monitoring your financial accounts and identity. If your information has already been compromised, combining a credit freeze with ongoing monitoring can give you broader visibility than relying on either measure alone.
How to Protect Your Identity While Your Credit Is Unfrozen
When your credit is temporarily unfrozen, legitimate lenders can access the credit report you’ve made available. That access may be necessary when you’re applying for a mortgage, auto loan, credit card, personal loan, or another financial product—but it also means your security freeze isn’t providing its normal barrier against new-account fraud during that period. A credit freeze generally prevents prospective creditors from accessing your file, making it harder for an identity thief to open new credit in your name.
An important part of how to unfreeze your credit is protecting your identity during that access window. You don’t need to panic or avoid applying for credit. Instead, keep the window controlled, watch for suspicious activity, and restore the freeze when legitimate lenders are finished.
1. Unfreeze Only the Credit Bureau the Lender Needs
Before lifting anything, ask the lender which credit bureau it plans to check.
If the lender only needs your Experian report, for example, you may not need to temporarily unfreeze Equifax and TransUnion too. The FTC specifically recommends identifying which bureau the lender will use and lifting the freeze only at that bureau when possible.
This limits the number of credit files that are accessible while you’re applying.
It’s a simple principle:
Only open what the legitimate lender actually needs.
2. Use a Temporary Lift Instead of Permanently Removing the Freeze
If you’re only applying for credit, consider a temporary credit freeze lift rather than permanently removing your security freeze.
A temporary lift lets you choose a period during which your credit file can be accessed. Once that period ends, the freeze can return without you having to permanently leave the report accessible. The CFPB confirms that consumers can temporarily lift a freeze and that placing or lifting a security freeze is free.
This is especially useful when you’re rate shopping for a mortgage or auto loan and know approximately how long lenders will need access.
3. Watch Your Credit Reports for Activity You Don’t Recognize
While your credit is unfrozen, pay attention to what’s appearing on your credit reports.
Warning signs can include:
- A credit inquiry from a company you don’t recognize
- A new account you didn’t open
- Incorrect personal information
- An unfamiliar balance or debt
- Other unexpected changes to your credit file
The CFPB identifies unfamiliar accounts and credit inquiries from companies you haven’t contacted as possible signs of fraud or identity theft.
Checking your reports can help you catch suspicious activity instead of discovering it months later.
4. Monitor Your Existing Financial Accounts Too
Your credit reports aren’t the only place identity fraud can appear.
Review your bank and credit card accounts for transactions, withdrawals, account changes, or other activity you don’t recognize. The FTC recommends reviewing bills, bank statements, and credit reports for signs of identity theft.
This matters because even a fully active credit freeze doesn’t prevent every form of identity theft. The CFPB notes that a freeze can help prevent fraudulent new accounts, but it doesn’t prevent an identity thief from taking over an existing account.
5. Be Extra Careful With Phishing During the Application Process
Applying for financing can generate legitimate emails, calls, texts, and account notifications. That can make it harder to distinguish genuine lender communications from phishing attempts.
Don’t provide your Social Security number, passwords, verification codes, or financial information simply because someone claims to represent your lender.
If a message seems suspicious, don’t use the phone number or link contained in the message. Instead, contact the lender using contact information you independently know is legitimate.
The CFPB warns that scammers impersonate financial institutions and government agencies when attempting to obtain money or personal information.
6. Protect the Accounts Connected to Your Identity
Credit security is only one part of identity security.
Your email account, banking accounts, credit cards, mobile phone account, and other important services can contain valuable personal information or provide pathways into additional accounts.
Use strong, unique passwords and enable multi-factor authentication where available. Also pay attention to unexpected password-reset messages or verification codes you didn’t request.
Someone who already possesses pieces of your personal information may try to obtain the remaining information through phishing or account takeover attempts.
7. Consider a Fraud Alert If You Suspect Identity Theft
A fraud alert and credit freeze aren’t the same thing.
A freeze generally restricts prospective creditors from accessing your credit file. A fraud alert instead tells businesses to take additional steps to verify your identity before granting new credit.
If you believe you are—or may soon become—a victim of identity theft or fraud, the CFPB says you can place an initial fraud alert on your credit report.
One useful difference is that you don’t have to contact all three nationwide credit bureaus individually for a fraud alert. When you place one with one of them, that bureau must notify the other two.
8. Consider Credit or Identity Monitoring for Additional Visibility
If you’re concerned about identity theft—particularly after a data breach—you may want more active monitoring while your credit is unfrozen.
Credit monitoring services generally watch your credit reports for changes and send alerts when certain activity occurs. Broader identity monitoring services may monitor personally identifiable information across credit applications, public records, websites, and other sources, depending on the service.
This is where buyer intent becomes important: don’t assume every identity theft protection service provides the same coverage.
When comparing paid services, look closely at features such as:
- Credit monitoring coverage
- Identity monitoring
- Alert speed and notification options
- Identity theft recovery assistance
- Identity theft insurance and its limitations
- Family coverage
- Account-security features included with the plan
The CFPB recommends understanding exactly what you’re getting before paying for identity monitoring because features and prices can vary significantly.
Monitoring should also be viewed as an alert system, not a guarantee that identity theft won’t happen. The CFPB cautions that most credit monitoring services don’t prevent personal information from being stolen; they primarily notify you about certain changes after they occur.
9. Restore the Freeze When the Credit Check Is Finished
Once the lender confirms that it has successfully pulled your credit and no additional authorized credit checks are needed, restore the freeze if it isn’t already scheduled to return automatically.
The FTC recommends putting the freeze back in place once lenders no longer need access to your credit report.
If you temporarily lifted the freeze for a specific period, verify that the freeze has returned when that period ends.
If you permanently removed it, you’ll need to place a new security freeze if you want the restriction restored.
Protecting your identity while learning how to unfreeze your credit comes down to controlling access rather than avoiding it altogether. Lift only the credit report a legitimate lender needs, keep the access period limited, watch your credit and existing financial accounts, and consider additional identity monitoring if you want broader alerts and recovery features. Once the authorized credit checks are finished, restoring the freeze gives you back an important layer of protection against fraudulent new accounts.
Can Identity Theft Protection Help After You Unfreeze Your Credit?
Yes. Identity theft protection can provide an additional layer of monitoring and recovery support after you unfreeze your credit, particularly if you’re concerned that your Social Security number or other personal information has already been exposed.
👉 If you want broader identity monitoring, credit alerts, and recovery support in one service, see what Aura includes and check the latest plans.
However, identity theft protection and a credit freeze do different jobs. A security freeze restricts prospective creditors from accessing your credit file, which can make it harder for an identity thief to open new credit accounts. Identity theft protection services generally focus more on monitoring, alerts, and recovery assistance.
That’s important when learning how to unfreeze your credit. Once you temporarily lift a freeze for a legitimate credit application, monitoring can give you additional visibility into certain activity while your report is accessible.
What Can Identity Theft Protection Monitor?
Coverage varies significantly depending on the provider and plan.
According to the CFPB, identity monitoring services may monitor personally identifiable information in places such as credit applications, public records, websites, and other sources for unusual activity that could indicate identity theft. Some services also include credit monitoring and identity recovery assistance.
Depending on the service you choose, monitoring could include:
- Changes to your credit reports
- New credit inquiries
- New accounts appearing on your reports
- Changes to certain personal information
- Public-record activity
- Certain online exposures of personal information
- Other potential indicators of identity misuse
The FTC notes that credit monitoring services may alert you when a company checks your credit history, a new loan or credit card appears, or certain personal information on your report changes.
That can be useful during a temporary credit freeze lift because you’re already expecting legitimate activity. An alert can help you compare what you’re seeing against the credit applications you actually authorized.
Identity Theft Protection Doesn’t Replace Your Credit Freeze
This distinction is critical.
You shouldn’t permanently remove your security freezes simply because you purchased an identity theft protection service.
The CFPB cautions that most monitoring services don’t stop your personal information from being stolen. They primarily alert you to certain activity after it occurs. A security freeze, on the other hand, generally prevents prospective creditors from accessing your credit file and can help stop fraudulent new accounts before they’re opened.
Think of the two protections as performing separate jobs:
Credit freeze: restricts access.
Identity monitoring: watches for certain warning signs.
Recovery assistance: helps you respond if identity theft occurs.
Using multiple layers can provide broader protection than expecting one tool to handle every type of identity fraud.
Why Monitoring Can Matter While Your Credit Is Unfrozen
Suppose you’re applying for an auto loan.
You temporarily lift your credit freeze so the lender can access your report. During that period, you expect to see a legitimate credit inquiry related to your application.
But what if another unfamiliar credit inquiry or account suddenly appears?
Credit monitoring may help bring certain unexpected credit-file changes to your attention. The FTC recommends reviewing credit reports because accounts you don’t recognize can be a sign of identity theft.
That doesn’t mean every alert indicates fraud. You still need to investigate what caused it.
But faster awareness can give you an opportunity to determine whether the activity belongs to you.
Identity Protection Can Monitor More Than Credit
This is one reason someone might consider a broader identity theft protection service rather than basic credit monitoring alone.
Credit monitoring primarily focuses on your credit reports. Identity monitoring may look for your personally identifiable information across additional sources, depending on the service.
That’s relevant because a credit freeze doesn’t protect against every form of identity theft.
For example, freezing your credit doesn’t stop someone from making unauthorized charges on an existing account. The FTC specifically recommends continuing to monitor bank, credit card, and insurance statements even when your credit is frozen.
So when comparing identity theft protection plans, don’t focus exclusively on whether the service advertises “credit monitoring.” Look at the entire monitoring package.
Recovery Assistance Can Be Valuable If Identity Theft Actually Happens
Monitoring tells you something may be wrong. Recovery assistance is about what happens after you’ve discovered a problem.
The CFPB notes that some identity theft services may help consumers correct problems after identity theft occurs.
The FTC says identity recovery services may provide counselors or case managers who can help with tasks such as communicating with creditors, placing freezes, and working through recovery documents.
This can be one of the more meaningful differences between simply checking your credit yourself and paying for a broader identity protection plan.
If you’re comparing services after learning how to unfreeze your credit, look beyond flashy dashboards and credit scores. Consider what kind of assistance you would actually receive if your identity were stolen.
What About Identity Theft Insurance?
Some identity theft protection plans include insurance, but read the coverage carefully.
Identity theft insurance generally isn’t the same thing as reimbursement for every dollar a criminal steals.
The FTC explains that policies may cover certain expenses associated with recovering your identity, such as document costs, postage, lost wages, or legal fees, depending on the policy. Coverage limitations, exclusions, and deductibles can apply.
Before paying extra for a plan because it advertises a large insurance amount, check:
- What expenses actually qualify
- Whether stolen funds are covered
- Deductibles
- Coverage limits
- Exclusions
- Documentation requirements
The headline insurance amount shouldn’t be the only reason you choose a service.
Do You Need to Pay for Identity Theft Protection?
Not necessarily.
There are several steps you can take yourself for free. You can freeze your credit, review your credit reports, monitor financial statements, use fraud alerts when appropriate, and respond directly to suspicious activity.
The CFPB specifically recommends understanding what you’re getting before paying for identity monitoring because prices and features vary widely.
A paid service may make more sense if you value having multiple types of monitoring consolidated in one place, want automated alerts, need coverage for multiple family members, or want access to professional recovery assistance if something goes wrong.
When Identity Theft Protection May Be More Worth Considering
Identity theft protection may deserve a closer look if:
- Your Social Security number has been exposed.
- You’ve received a serious data-breach notification.
- You’ve previously experienced identity theft.
- You want broader monitoring than you realistically will perform yourself.
- You want alerts covering multiple areas of your identity.
- You want professional recovery assistance available if fraud occurs.
- You’re protecting several members of your household.
The FTC specifically notes that credit freezes are especially important when sensitive information has been exposed or identity theft has already occurred.
Even if you choose paid identity protection, keeping your security freezes in place when you aren’t actively applying for credit can remain an important part of your overall strategy.
Identity theft protection can be useful after learning how to unfreeze your credit, but it should be viewed as a complement to your security freeze rather than a replacement for it. A temporary lift gives legitimate lenders access when you need financing, monitoring can help alert you to certain suspicious activity, and recovery services can provide assistance if identity theft actually occurs. Once the lender has completed the authorized credit check, restoring your freeze while continuing to monitor your identity gives you multiple layers of protection instead of relying on a single defense.
What to Look for in an Identity Theft Protection Service
If you’re considering identity theft protection after temporarily lifting a credit freeze, don’t choose a service based only on the biggest insurance number or the longest feature list. Look at what the service actually monitors, how quickly it alerts you, and what help you’ll receive if identity theft occurs.
This matters when learning how to unfreeze your credit because a credit freeze and identity theft protection perform different jobs. A freeze restricts prospective creditors’ access to your credit file, while identity monitoring services may watch credit applications, public records, websites, and other sources for unusual activity.
The CFPB also cautions that prices and services vary widely, so it’s important to understand exactly what you’re buying before subscribing.
1. Three-Bureau Credit Monitoring
Start by checking how many credit bureaus the service monitors.
Some plans may monitor activity at only one credit bureau, while others monitor Equifax, Experian, and TransUnion. The FTC specifically recommends asking which of the three bureaus a credit-monitoring service watches before subscribing.
Three-bureau monitoring can provide broader visibility because suspicious credit activity might initially appear on one credit report rather than all three.
Look for alerts involving activity such as:
- New credit inquiries
- New credit cards or loans
- Changes to account information
- Certain changes to personal information
- Other significant credit-report changes
If you’re comparing identity theft protection plans, don’t assume the cheapest tier automatically includes three-bureau monitoring. Check the actual plan details before buying.
2. Identity Monitoring Beyond Your Credit Reports
Credit monitoring shouldn’t be the only feature you evaluate.
Identity monitoring can look for signs of misuse that may not immediately appear on a traditional credit report. According to the FTC, identity monitoring services may check databases for activity involving change-of-address requests, court records, certain utility or wireless accounts, payday-loan applications, and websites where stolen information may be traded.
The CFPB similarly notes that identity monitoring can involve personally identifiable information found in credit applications, public records, websites, and other sources.
That broader coverage may be particularly attractive if your Social Security number or other sensitive information has already been exposed.
👉 If broader identity monitoring is one of your priorities, check Identity Guard’s current plans and features to see which level of protection fits what you want monitored.
3. Fast, Useful Alerts
Monitoring isn’t very useful if you don’t find out about suspicious activity until much later.
Look for a service that provides convenient alert options, such as:
- Mobile app notifications
- Text alerts
- Email alerts
- Account-dashboard notifications
The CFPB notes that credit-monitoring services commonly notify consumers of changes by email, text message, or phone.
Also consider the quality of the alerts. You want enough information to understand what changed and determine whether you recognize the activity.
For example, if you’ve temporarily lifted a freeze to finance a vehicle, an alert about the lender’s authorized credit inquiry would make sense. An inquiry from a company you’ve never contacted deserves investigation.
4. Identity Theft Recovery Assistance
Monitoring tells you something may have happened. Recovery assistance helps you deal with what comes next.
This can be one of the biggest reasons to consider a paid identity theft protection service.
The FTC explains that identity recovery services may provide counselors or case managers who help victims communicate with creditors, place credit freezes, review necessary documents, and work through other recovery steps. Some services may even communicate with institutions on your behalf if you formally authorize them to do so.
When comparing plans, find out:
- Whether recovery assistance is included
- Whether you get a dedicated specialist
- Whether support is available when you need it
- What the specialist will actually do for you
- Whether family members receive the same recovery support
5. Identity Theft Insurance—and What It Actually Covers
A large insurance figure can look impressive, but don’t judge a service solely by the advertised amount.
Read the policy.
The FTC explains that identity theft insurance may cover certain recovery-related expenses, including document costs, postage, lost wages, and legal fees, depending on the policy. It also warns that identity theft insurance generally doesn’t simply reimburse every dollar a scammer steals, and coverage can be subject to exclusions and other limitations.
Before buying, check:
- Total coverage limits
- Coverage for stolen funds, if any
- Lost-wage coverage
- Legal-expense coverage
- Deductibles
- Exclusions
- Reimbursement requirements
- Limits for individual family members
Don’t let a large headline number substitute for reading what the policy actually covers.
6. Monitoring for Exposed Personal Information
If your Social Security number, email address, phone number, or other identifying information has been compromised, look closely at what personal information the service monitors.
Some identity monitoring services search sources beyond traditional credit reports for indications that your information may be circulating or being misused.
However, no monitoring service can see everything.
The FTC points out that identity monitoring may not detect certain forms of fraud involving tax returns, Medicare, Medicaid, Social Security benefits, or unemployment benefits.
That’s an important limitation to understand before paying for a plan marketed as comprehensive protection.
7. Family Coverage
If you’re protecting more than yourself, compare the family plan carefully.
Don’t assume “family protection” means every household member receives every feature available to the primary subscriber.
Check:
- How many adults are covered
- How many children are covered
- Which monitoring features apply to children
- Whether every adult receives credit monitoring
- Whether recovery assistance covers everyone
- Whether insurance limits are shared or separate
- Whether each adult gets their own alerts and account access
Then compare the total household price, not just the advertised introductory monthly rate.
A slightly more expensive plan may provide better value if it replaces several separate individual subscriptions.
8. Clear Pricing and Cancellation Terms
Look beyond the promotional price.
The CFPB recommends checking trial periods, fees, cancellation requirements, and restrictions before accepting identity or credit monitoring—even when something is advertised as “free.”
Ask:
What will I actually pay after the introductory period ends?
Check whether the company charges monthly or annually, whether the subscription automatically renews, what features require a higher tier, and how cancellation works.
9. Account Security
There’s little benefit in trusting an identity protection company with sensitive information if your account itself isn’t well protected.
Before signing up, look at the security controls available for your account.
At minimum, consider whether the service provides strong authentication options and allows you to quickly recognize and respond to unusual account activity.
Use a unique password for the service and enable multi-factor authentication when available. Don’t reuse the same password you use for your email, bank, or other important accounts.
10. Don’t Confuse Monitoring With Prevention
This may be the most important thing to understand before buying.
Identity theft protection isn’t an invisible shield that guarantees nobody can steal your identity.
The CFPB cautions that most credit-monitoring services don’t prevent personal information from being stolen; instead, they alert consumers to certain activity after it occurs.
That’s why identity protection should complement—not replace—preventive measures such as a credit freeze.
If you’re learning how to unfreeze your credit because you’re applying for financing, you can temporarily lift the necessary freeze, allow the legitimate lender to complete its credit check, and then restore the freeze afterward. The FTC confirms that freezes are free to place and lift and can be restored once you’re finished applying.
The right identity theft protection service should give you features you’ll actually use—not simply the longest marketing checklist. Prioritize meaningful credit and identity monitoring, useful alerts, strong recovery assistance, clearly explained insurance, family coverage if you need it, and transparent pricing. Combined with responsible account security and restoring your credit freeze when lenders no longer need access, those features can provide broader visibility and support while keeping how to unfreeze your credit part of a layered identity-protection strategy.
Is Identity Theft Protection Worth It After You Unfreeze Your Credit?
Identity theft protection can be worth considering after you unfreeze your credit, especially if your Social Security number or other sensitive information has already been exposed, you want broader monitoring than you’ll realistically do yourself, or you value having professional recovery assistance available if identity theft occurs.
But it isn’t automatically necessary for everyone. If you’re unsure whether the extra monitoring and recovery support makes sense for you, learn whether you really need identity theft protection before paying for a service.
When you’re learning how to unfreeze your credit, it’s important to separate two different types of protection. A credit freeze restricts prospective creditors from accessing your credit file, while identity theft protection services generally focus on monitoring, alerts, and recovery assistance. The CFPB notes that identity monitoring services can watch personally identifiable information across credit applications, public records, websites, and other sources, depending on the service.
When Identity Theft Protection May Be Worth Paying For
A paid service becomes easier to justify when the features solve a problem you actually have.
It may be worth considering if:
- Your Social Security number has been exposed in a data breach.
- You’ve previously experienced identity theft.
- You want automated credit and identity alerts.
- You don’t want to manually monitor several sources yourself.
- You’re protecting multiple family members.
- You want access to professional identity recovery assistance.
- You want monitoring that extends beyond traditional credit reports.
- You value having several identity-protection features managed through one service.
This can be particularly relevant after a serious data breach. The FTC says credit freezes are especially important when your Social Security number or other sensitive information has been exposed or misused.
A paid identity protection service can then serve as another layer alongside that freeze rather than replacing it.
What Are You Actually Paying For?
This is the question to ask before subscribing.
Identity theft protection services can combine several features that you could otherwise manage separately.
Depending on the plan, you may be paying for:
Credit monitoring: Alerts about certain changes to your credit reports.
Identity monitoring: Searches for signs that your personally identifiable information may be appearing or changing in certain databases, websites, public records, or other monitored sources.
Recovery assistance: Access to specialists or case managers who can help if identity theft occurs.
Identity theft insurance: Coverage for certain eligible recovery expenses, subject to the policy’s limits and exclusions.
Convenience: Multiple monitoring and recovery features managed through one account.
The FTC explains that recovery services may provide counselors or case managers who help victims communicate with creditors, place freezes, and work through recovery documents.
That convenience and assistance—not just monitoring—can be a major part of what you’re paying for.
When You May Not Need a Paid Service
You can take several meaningful identity-protection steps without paying a monthly subscription.
For example, you can:
- Freeze your credit for free.
- Temporarily lift your freezes for free.
- Review your credit reports yourself.
- Monitor your bank and credit card statements.
- Place a fraud alert when appropriate.
- Use strong, unique passwords.
- Enable multi-factor authentication.
- Investigate suspicious activity yourself.
The CFPB specifically points out that free and low-cost alternatives exist, including security freezes, fraud alerts, and reviewing your credit reports yourself.
So if you’re disciplined about monitoring your own accounts and don’t need recovery assistance or broader identity monitoring, paying for another service may provide less additional value.
Don’t Pay for Monitoring You Already Have
Before buying anything, check the benefits you already receive.
The FTC notes that monitoring or identity-related services may sometimes be available through a bank, credit union, credit card provider, employer benefit program, or insurance company.
You may also receive complimentary monitoring following certain data breaches.
Compare those benefits with the paid plan you’re considering. If you’re already receiving the features you care about, another subscription could create unnecessary overlap.
Paid Identity Protection Doesn’t Mean Identity Theft Can’t Happen
This is one of the most important limitations to understand.
Paying for identity theft protection doesn’t guarantee that your identity won’t be stolen.
The CFPB warns that most credit-monitoring services don’t prevent personal information from being stolen. They primarily alert you after certain activity occurs.
That makes identity protection closer to an alarm system than an impenetrable wall.
You still need preventive measures such as protecting your Social Security number, securing your online accounts, watching for phishing attempts, monitoring financial activity, and keeping your credit frozen when you don’t need lenders to access it.
A Credit Freeze May Still Be Your Strongest Free Layer Against New-Account Fraud
Don’t permanently remove your freezes simply because you purchased identity theft protection.
A security freeze prevents prospective creditors from accessing your credit file, which can help prevent an identity thief from opening a new credit account in your name. The FTC recommends temporarily lifting the appropriate freeze when you need a legitimate credit check and restoring it afterward.
That means someone learning how to unfreeze your credit can use both tools together:
Need financing → Temporarily lift the necessary freeze → Complete the authorized credit check → Restore the freeze → Continue monitoring.
Consider the Cost Against the Features You’ll Actually Use
Don’t judge value based only on the monthly price.
A cheaper plan isn’t necessarily a better value if it leaves out the features you want, and an expensive plan isn’t automatically better because it has dozens of features.
The CFPB notes that prices and services offered by identity-monitoring providers vary widely and recommends understanding exactly what you’re getting before subscribing.
Compare features such as:
- One-bureau vs three-bureau credit monitoring
- Identity monitoring beyond credit
- Alert methods
- Recovery assistance
- Family coverage
- Identity theft insurance terms
- Account-security features
- Monthly vs annual pricing
- Renewal rates
- Cancellation requirements
Pay particular attention to promotional or “free” offers. The CFPB recommends checking for trial periods, fees, and cancellation requirements before enrolling.
Who May Get the Most Value From Identity Theft Protection?
The strongest buyer case isn’t simply someone who temporarily unfroze their credit.
It’s someone who wants ongoing monitoring and recovery support after the credit application is finished.
For example, paid protection may offer more value to someone whose Social Security number has been exposed and who wants broader monitoring, automated alerts, and access to recovery specialists than to someone who only needs to temporarily lift a freeze for one routine credit-card application.
The decision becomes less about fear and more about convenience, coverage, and how much monitoring you’re willing to handle yourself.
Identity theft protection can be worth considering after learning how to unfreeze your credit, but its value depends on what you’re actually buying and what protection you already have. If you want broader monitoring, convenient alerts, family coverage, or professional recovery support, a paid service may provide meaningful additional value. If you’re comfortable managing free credit freezes, reviewing your own reports, and monitoring your accounts yourself, you may decide you don’t need the extra subscription.
Either way, identity theft protection shouldn’t replace your credit freeze. Once legitimate lenders have completed their credit checks, restoring the freeze while continuing to monitor your identity gives you a stronger layered approach than relying on any single service.
Frequently Asked Questions About How to Unfreeze Your Credit
Even after you understand the basic steps for how to unfreeze your credit, there are a few less-obvious questions that can come up when you’re managing a security freeze. The answers below cover additional situations that haven’t already been addressed above.
Can I Check My Own Credit Report While My Credit Is Frozen?
Yes. You do not need to unfreeze your credit just to check your own credit report.
A security freeze restricts prospective creditors from accessing your credit file, but it doesn’t prevent you from requesting, viewing, or reviewing your own report. The CFPB specifically confirms that consumers can review their credit files while a freeze remains in place.
That means you can continue monitoring your credit without giving up the new-account protection provided by your freeze.
Do I Need to Unfreeze My Credit for a Credit Limit Increase?
It depends on whether the credit card issuer needs to access your credit report to process the request.
Existing creditors are among the entities that may still have access to your credit file while a freeze is active. However, the exact process for a credit limit increase can vary by issuer.
Before changing your freeze, ask the credit card company whether it needs you to lift the freeze and, if so, which credit bureau it plans to access.
There’s no reason to temporarily lift your credit reports unnecessarily if the issuer can complete the request without it.
Can I Still Use My Existing Credit Cards After Refreezing My Credit?
Yes. A credit freeze doesn’t shut down your existing credit cards or other existing credit accounts.
The freeze restricts access to your credit file for purposes such as opening certain new accounts. Existing creditors may continue to have access to your file in permitted circumstances.
So after completing your application and restoring your freeze, you can continue using your existing credit cards normally.
Do I Need to Unfreeze My Credit to Check My Credit Score?
No. A credit freeze doesn’t prevent you from checking your own credit information, and placing or lifting a freeze doesn’t affect your credit score.
You don’t need to remove an important security measure simply because you want to monitor your score.
Also remember that the score you see through a consumer service may not always be identical to the score a lender uses. Different credit-scoring models and versions can produce different scores.
Can I Have a Fraud Alert and a Credit Freeze at the Same Time?
Yes.
You can have both a fraud alert and a credit freeze on your credit reports. The two protections work differently.
A security freeze restricts prospective creditors from accessing your credit file. A fraud alert doesn’t block access; instead, it tells businesses to take steps to verify your identity before granting new credit.
The FTC specifically confirms that you can place a fraud alert even when a credit freeze is already active.
This combination may be particularly useful if you believe your personal information has been stolen or exposed.
Do I Need to Unfreeze My Credit for a Job Application?
Under federal credit-freeze law, generally no. The CFPB states that the federal security-freeze requirements don’t apply to someone requesting your credit report for employment purposes.
The FTC likewise states that you can apply for a job while your freeze remains in place.
If an employer tells you otherwise, ask exactly what type of report or background check it is attempting to obtain before changing your freeze.
Do I Need to Unfreeze My Credit to Rent an Apartment?
Under the federal security-freeze rules, tenant-screening requests aren’t covered by the freeze requirement in the same way as new-credit applications. The CFPB specifically identifies tenant screening as outside the federal law requiring security freezes.
The FTC also says that a credit freeze doesn’t prevent you from applying to rent an apartment.
However, landlords and screening companies can use different types of consumer reports. If you’re told that a frozen report is preventing your application from moving forward, ask which report the company is trying to access before lifting anything.
Do I Need to Unfreeze My Credit When Buying Insurance?
Generally, a federal security freeze doesn’t need to be lifted solely because you’re applying for insurance. The CFPB says the federal law governing security freezes doesn’t apply to requests for credit reports for insurance purposes.
The FTC similarly states that a credit freeze doesn’t prevent you from buying insurance.
If an insurer says it cannot access information it needs, find out exactly which consumer report is involved before temporarily removing a freeze.
Can Someone Else Unfreeze My Credit Without My Permission?
Credit bureaus use identity-verification procedures when consumers manage security freezes, which is one reason protecting your credit-bureau accounts and associated credentials is important.
If you receive an unexpected notification indicating that a freeze was lifted or changed, don’t ignore it.
Sign in through the credit bureau’s official website—not a link in an unexpected email or text—and verify your freeze status. If you discover a change you didn’t authorize, contact the bureau and review your credit reports for unfamiliar activity.
If you believe identity theft has occurred, the FTC recommends reporting it and following an individualized recovery plan.
Can I Unfreeze My Credit If I No Longer Have My Original Freeze Information?
Don’t assume that losing old freeze paperwork means your credit must remain frozen forever.
The process for recovering access depends on the credit bureau and its current identity-verification procedures. If you can’t access your freeze through your normal account, use the bureau’s official recovery or customer-support process.
Avoid giving sensitive information to a third-party website claiming it can “unlock” your credit for a fee. Federal law gives you the right to freeze and unfreeze your credit with the nationwide credit reporting companies for free.
Will Unfreezing My Credit Remove a Fraud Alert?
No. A credit freeze and fraud alert are separate protections.
A fraud alert tells creditors to verify your identity before granting certain new credit, while a security freeze restricts prospective creditors’ access to your credit file.
Temporarily lifting your security freeze doesn’t, by itself, mean you’re requesting removal of an existing fraud alert.
This can matter if you’re learning how to unfreeze your credit after suspected identity theft. You may need to temporarily make a report accessible for a legitimate application while still wanting the additional identity-verification requirement provided by your fraud alert.
Can I Apply for Credit Again Immediately After Refreezing My Reports?
You can apply for credit whenever you choose, but if a new lender needs access to a credit report you’ve already frozen again, you’ll need to temporarily lift the appropriate freeze before that lender can perform the necessary credit check.
That doesn’t mean you made a mistake by refreezing.
Security freezes are designed to be managed as your needs change. They’re free to place and lift, and the CFPB notes that consumers can temporarily lift them for a specified period when they need access.
If you frequently shop for financial products, planning your temporary access period can be more convenient than repeatedly lifting and restoring the freeze.
The most important thing to remember about how to unfreeze your credit is that you don’t need to lift a security freeze for every situation involving your credit or identity. Determine whether access is actually required first. When a legitimate creditor does need your report, temporarily lift only what’s necessary, complete the application, and restore the protection when the authorized access is finished.
Conclusion: How to Unfreeze Your Credit
Knowing how to unfreeze your credit gives you the flexibility to apply for a mortgage, auto loan, credit card, or other financial product without permanently giving up the protection of a security freeze.
For most credit applications, the practical approach is simple: find out which credit bureau the lender plans to use, temporarily lift that freeze for the period needed, confirm the lender has successfully completed its credit check, and then allow the freeze to return or restore it yourself.
The FTC specifically recommends identifying which bureau a lender will use when possible, lifting the freeze at that bureau, and putting it back in place once the credit check is finished. Credit freezes are also free to place and lift.
Temporary Access Is Usually Better Than Leaving Your Credit Open
If you’re only unfreezing your credit because you’re applying for financing, there’s usually little reason to leave the report accessible indefinitely.
A temporary credit freeze lift allows you to specify the period during which your report should be available. The CFPB confirms that temporary lifts are free and that consumers can choose the period of the lift.
This can be particularly useful when you’re:
- Applying for a mortgage
- Financing or leasing a vehicle
- Applying for a credit card
- Taking out a personal loan
- Refinancing existing debt
- Comparing offers from multiple lenders
If you’re shopping among several lenders, give yourself enough time for the authorized credit checks to occur. If you’re dealing with only one lender, ask which bureau it needs before unnecessarily lifting all three freezes.
Don’t Confuse Unfreezing With Removing Your Protection Permanently
Unfreezing your credit doesn’t have to mean permanently removing your security freeze.
That’s one of the biggest takeaways from understanding how to unfreeze your credit.
You can temporarily lift the freeze, complete your financial application, and restore the restriction afterward. Your credit score isn’t affected simply because you place or lift a security freeze.
And if you only lift one bureau’s freeze, the freezes you’ve maintained at the other bureaus remain separate.
Restore the Freeze When You’re Finished
Once the legitimate lender has completed the credit check, keeping your freeze in place can continue making it harder for an identity thief to open certain new accounts in your name.
A security freeze generally prevents prospective creditors from accessing your credit file. Because lenders typically need that information before approving new credit, the restriction can help stop fraudulent new-account applications.
The FTC recommends temporarily lifting a freeze when you need lenders to access your report and putting it back once that access is no longer necessary.
That’s particularly important if your Social Security number or other sensitive personal information has already been exposed in a data breach.
A Credit Freeze Is Powerful—but It Isn’t Complete Identity Protection
Even after you restore all three credit freezes, continue watching your identity and financial accounts.
A security freeze is primarily aimed at restricting access for new credit. It doesn’t prevent every type of identity theft, including attempts to take over existing accounts.
That’s why a broader identity-protection strategy can include:
- Reviewing your credit reports
- Monitoring bank and credit card transactions
- Protecting your Social Security number
- Using strong, unique passwords
- Enabling multi-factor authentication
- Watching for phishing and impersonation scams
- Investigating unfamiliar credit activity quickly
You can also use a fraud alert if your circumstances call for one. Unlike a freeze, a fraud alert doesn’t block access to your credit report; it tells lenders to take additional steps to verify your identity before granting new credit.
Consider Whether Additional Identity Monitoring Fits Your Needs
If your personal information has already been exposed—or you simply want more automated monitoring—you may also consider an identity theft protection service.
Paid protection isn’t necessary for everyone. The CFPB notes that consumers have free options, including security freezes, fraud alerts, and reviewing their own credit reports. It also cautions that monitoring services don’t necessarily prevent personal information from being stolen.
However, a paid service may be worth considering if you value features such as broader identity monitoring, automated alerts, family coverage, or professional recovery assistance.
If those features match what you’re looking for, compare our best identity theft protection services to see which options provide the monitoring, alerts, recovery support, and coverage that fit your needs.
The key is to compare what you’re actually getting rather than buying based on fear or a large advertised insurance amount.
Identity theft protection should complement your credit freeze—not replace it.
The Bottom Line
The safest way to approach how to unfreeze your credit is to think of it as controlled access.
You don’t have to choose between protecting your credit and applying for the financial products you need. Temporarily lift the appropriate freeze, give the legitimate lender enough time to complete its credit check, and restore the freeze when that access is finished.
If you’re concerned about identity theft, continue monitoring your credit and financial accounts after the freeze returns. And if you want broader automated monitoring and recovery support, compare identity theft protection services based on the features you’ll actually use.
The goal isn’t to keep your credit permanently accessible. It’s to open access only when you need it, complete the legitimate credit check, and then put your protection back in place. That makes how to unfreeze your credit less about removing security and more about staying in control of who can access your credit—and when.